
PATRICK'S QUICK ANSWER
Yes, you can house hack a duplex or fourplex with FHA or VA, and it is the smartest move for most first-time owners. FHA lets you buy a multi with 3.5% down as long as you live in one unit, and VA allows up to four units with zero down. I weigh the unit rents, your qualification, and whether the other units cover the payment. One purchase can produce a home and rental income.
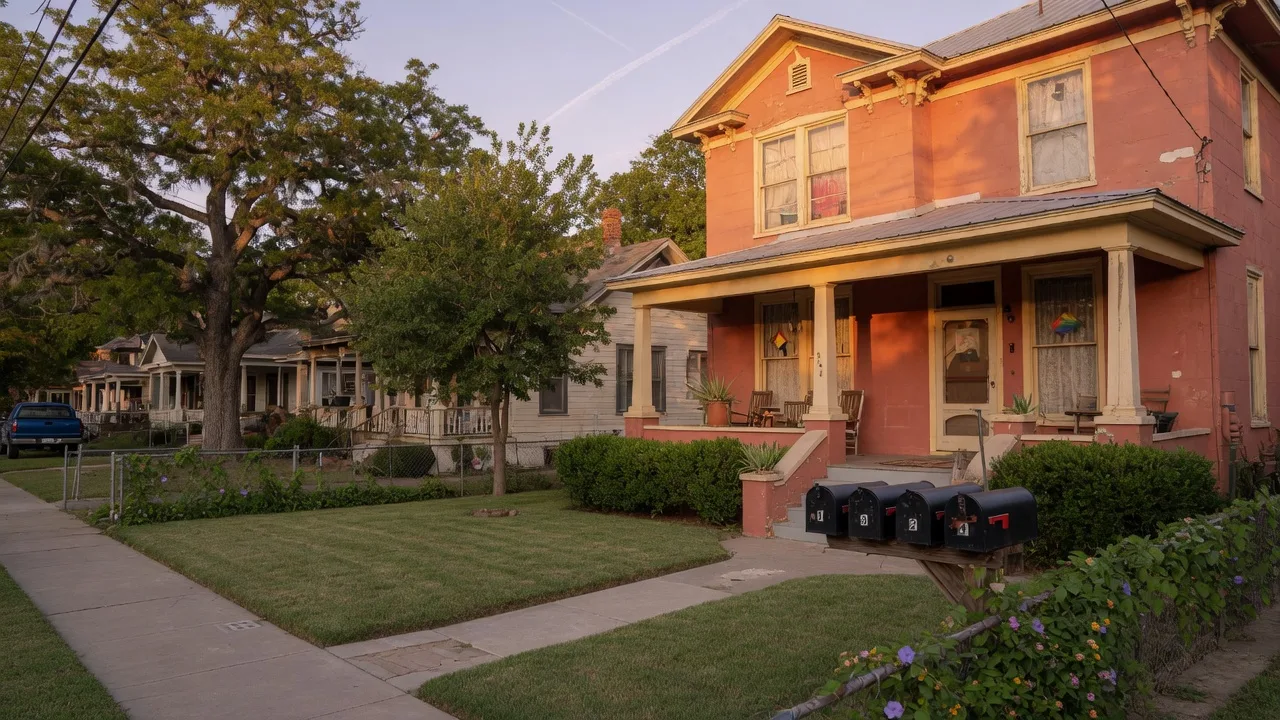
Patriot Nation, the fastest path to rental wealth does not start with a landlord hat and a down payment on an investment property, it starts with you moving into one unit of a duplex or fourplex and letting your neighbors pay the mortgage. House hacking is real, and FHA and VA are its best friends. Here is how the financing works in 2026, the math that makes it work, and the honest workload.
Find me a 2 to 4 unit near your work and your budget.
I run the FHA and VA qualification on the actual building, rents included, so you know the real payment before you fall for the floor plan.
The FHA path: 3.5% down on your own fourplex
FHA will finance a 2 to 4 unit property at 3.5% down when you occupy one unit as your primary residence. That single requirement, owner occupancy, is the entire trick, because it unlocks first-time-buyer financing on an income property. Two rules to know:
- Rental income counts. FHA uses roughly 75% of the projected market rent from the other units to offset the housing payment, which is the qualification engine.
- 3 and 4 unit self-sufficiency. For triplexes and fourplexes, FHA requires the property's rental income to cover the mortgage payment at 75% of rent, a stricter check than on a duplex.
- Limits are generous in Bexar County: 2026 FHA limits run up to $714,000 for a duplex, $863,100 for a triplex, and $1,072,600 for a fourplex, so the room is real.
The self-sufficiency test is why the fourplex math runs best on a priced-right building, and it is exactly the kind of thing I model before you make an offer. The multi-family investing explainer covers the underwriting angles in more depth.
The VA path: zero down, no PMI, up to a fourplex
For eligible veterans and active-duty families, the VA loan finances up to a fourplex with zero down and no monthly mortgage insurance, as long as you occupy one unit. Rental income from the other units offsets the payment, and the only recurring cost is the VA funding fee for those who do not qualify for an exemption. Add military-area rental demand near JBSA, and a VA house hack around San Antonio can be the single best financial move a military family makes, and I will help you structure it before the next PCS.
The lender's math on rental income
Rounded example, not a quote
Say a fourplex rents at $1,200 per unit. The appraiser-estimated gross rent is $4,800 a month, and the lender counts 75% of that, about $3,600, against the housing payment.
The 75% factor covers vacancy and maintenance by design, so the counted number is intentionally conservative. Your actual payment depends on price, rate, taxes, and insurance.
The rental income qualification explainer covers how different loan programs treat that 75% factor, and the full program-by-program comparison lives in the investment loan options guide.
The tenants pay the mortgage, but you run the building.
Vacancies, repairs, and tenants are real work. I pair the financing with the honest operating math so the house hack serves you instead of owning you.
Where the inventory sits in San Antonio
Multi-unit inventory is not spread evenly. The classic pockets:
- Central San Antonio: older duplexes and fourplexes in established corridors, where price per unit stays within reach for first-time house hackers.
- Near JBSA and the military footprint: constant rental demand from PCS families, a natural fit for a VA house hack.
- University and hospital areas: reliable tenant pools and steady demand year round.
- Northeast and north corridors: newer multi-unit inventory, often at higher price points with newer systems.
My San Antonio house hacking overview layers the market picture over this foundation, and the San Antonio community guide helps narrow the search by neighborhood.
The honest workload reality
House hacking is a job with a mortgage attached: tenant screening, rent collection, repairs, and the occasional 2 a.m. call. The money math works because you trade that work for equity, the tenants pay down the principal, and your own housing cost drops. Autopilot it with good systems and reserves, or hire management when the scale justifies it, but never pretend the work does not exist. The strategy overview in the multi-family guide includes the operating truth most sales offices skip.
Frequently Asked Questions
What is house hacking? Tap to expand
Can I use an FHA loan on a duplex or fourplex? Tap to expand
Can I use a VA loan on a multi-unit property? Tap to expand
How does rental income help me qualify? Tap to expand
Where does multi-unit inventory concentrate in San Antonio? Tap to expand
Move in as a buyer, not a renter, and let the building pay you back.
I finance and negotiate multi-unit purchases across San Antonio, from the central fourplex pockets to military rental corridors, and I will show you the real numbers before you commit to the landlord life.
Patrick Kevin Fagan
Senior Mortgage Loan Officer and Texas REALTOR | AXEN Realty LLC | Greater San Antonio and Texas Hill Country
Licensed Sales Agent | 454749 | TX
Sincerely, Patrick Kevin Fagan
FHA and VA multi-unit rules reflect published 2026 guidelines and FHA limit figures for Bexar County; loan limits and program details are confirmed at application. Rent and payment figures are labeled examples, not quotes.

