
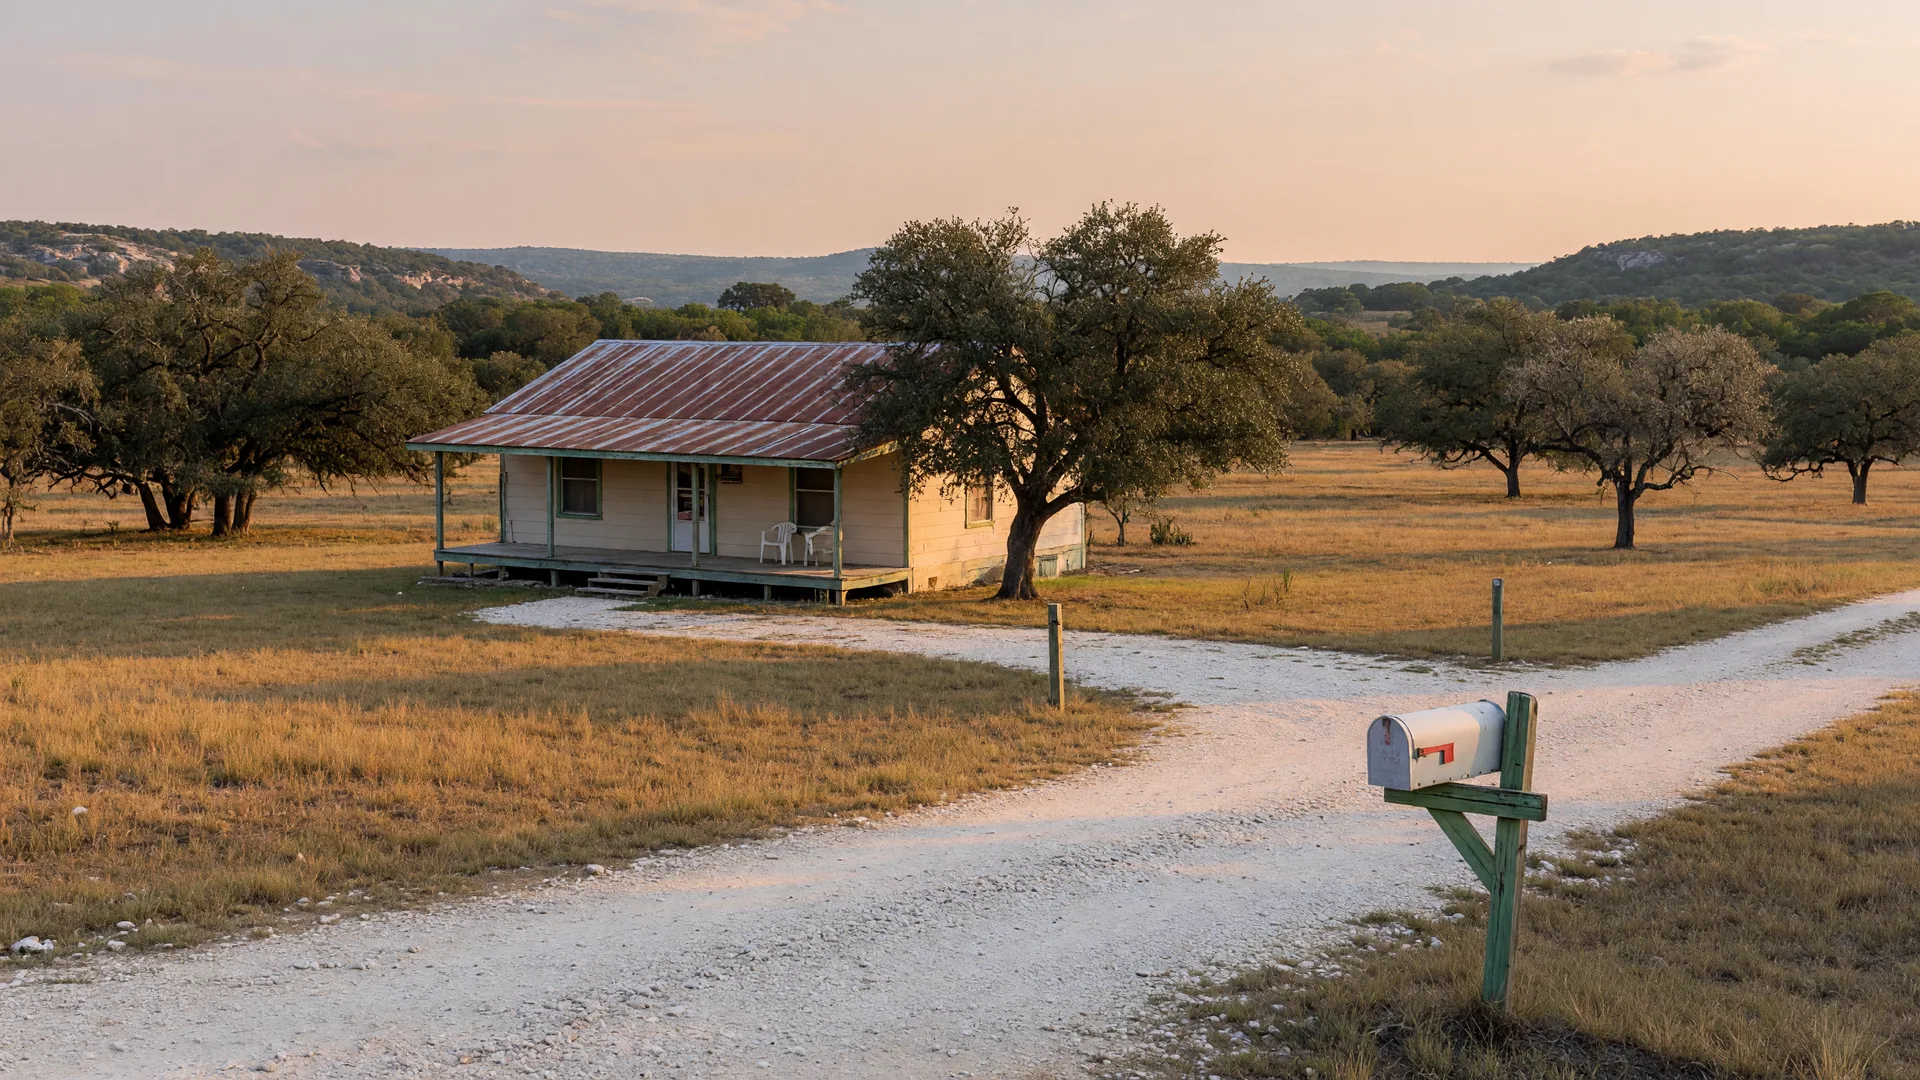
Patrick's Quick Answer
The USDA loan is a zero-down, low-rate option for homes in eligible rural areas, and parts of Bulverde and Spring Branch can qualify depending on the exact property location and your household's income. It's not based on the town's vibe, it's based on a map and your income limits. Start by running the property address through the official USDA eligibility tool and checking the current income limits for Comal and Bexar counties, then confirm the home itself meets program standards.
Buyers hear "USDA" and picture farms. In reality, it's one of the best zero-down tools for the right Hill Country property, and the reason most people never use it is that nobody checked the map. Let's fix that.
What the USDA loan is
The USDA Rural Development Guaranteed Loan is a government-backed mortgage for homes in eligible rural and small-town areas. On the right property it means: no down payment at all, competitive fixed rates, and a very low monthly mortgage insurance cost compared with FHA.
It's not a first-time buyer program, current homeowners can use it too, and it's not limited to farms. A standard suburban-style house on a lot can qualify if it sits inside an eligible area. The two gates are the map and your income.
How eligibility works
Two separate checks, both of which you can run yourself in about ten minutes:
- Area eligibility. The property must fall inside USDA's eligible area map, which is based on population and rural character, not beauty. Run the address on the official USDA income and property eligibility site: eligibility.sc.egov.usda.gov. This is the source of truth; no third-party tool replaces it.
- Income eligibility. Your household income must stay at or below USDA's limit for the county and household size. The limits are published and updated by USDA, and they vary between Comal and Bexar counties, so check the current numbers for the county the property sits in.
Household income counts the adults in the home, not just the buyer, so a married couple where one spouse earns above the limit can disqualify even when the buyer's own income is modest. Run the check early in the process.
Where Bulverde and Spring Branch fit
The honest answer is "it depends on the exact address." USDA eligibility is drawn on a property-level map, and the corridor north of San Antonio has a patchwork of eligible and ineligible pockets as the metro boundary creeps outward in both directions. Some Bulverde and Spring Branch addresses qualify; some, especially inside the denser subdivisions close to the city line, don't.
This is exactly why I tell buyers not to assume either way. Take the address you're considering, verify it on the USDA tool, and get your lender's confirmation that the map shows eligible for that specific parcel. Ineligible today can also change over time, but always buy on the map that's current when you apply.
Here's the key: eligibility is an address-level fact, not a town-level rumor. Ten minutes on the official USDA map answers the question for any home you're considering.
USDA vs. FHA vs. VA
If you're deciding between programs, here's the short version:
- USDA: zero down, low monthly insurance, but area and income gates apply.
- FHA: 3.5% down, more forgiving credit, but higher monthly mortgage insurance that lasts the life of the loan on most new loans.
- VA: zero down, no monthly insurance, but you need the military benefit.
For a qualifying buyer in an eligible area, USDA usually beats FHA on monthly cost because the insurance is so much cheaper. For a veteran, VA usually wins. My USDA zero-down comparison and the financing guide lay out the full side-by-side.
The catch to plan for
USDA carries property standards: the home has to be safe, sound, and sanitary, which is the program's polite way of saying it won't fund a fixer with peeling paint, an ungrounded outlet, or a sagging roof. Appraisers check these items, and repairs become conditions to close.
On Hill Country acreage, that also means the well and septic get real scrutiny, which is a good thing if you do your inspections during the option period. USDA has both more to gain and more requirements to manage than a conventional loan, so a lender who has closed USDA deals in Comal and Bexar counties matters. My USDA explained covers the program mechanics in more detail.
Think you might qualify? Let's run the map and the math.
I'll check the property's USDA eligibility, your household income against the current limits, and compare the zero-down USDA route against FHA and VA on your real numbers.
Frequently Asked Questions
Is Bulverde or Spring Branch eligible for USDA loans? Tap to expand
Can I use a USDA loan on a home with acreage? Tap to expand
What credit score do I need for USDA? Tap to expand
Zero down might be closer than you think
USDA is one of the most underused programs in the Hill Country, mostly because buyers never checked. Let's see if your property and your income make it available.
Patrick Kevin Fagan
Loan Officer and Realtor | AXEN Realty LLC | San Antonio and Texas Hill Country
Licensed Sales Agent | 454749 | TX
Sincerely, Patrick Kevin Fagan
USDA details in this post are directional and change with program rules, income limits, and the eligibility map. Always verify the current official USDA guidance and your lender's requirements for the exact property.

