
Patrick's Quick Answer
Yes, construction-to-permanent financing is the standard route for a custom Hill Country build, and the governing rule is Fannie Mae Selling Guide B5-3.1-01 (06/04/2025): the loan is allowed as one closing or two separate closings, the borrower must hold title to the lot, and the lender keeps a Form 1004D (or a completion alternative) plus a certificate of occupancy or its equivalent. Attached condo units and co-ops are ineligible. The details that vary by lender, maximum LTV, reserves, interest reserve and draw rules, were not verified in this pass, so check Fannie Mae B5-3.1-02 and the lender's construction matrix.
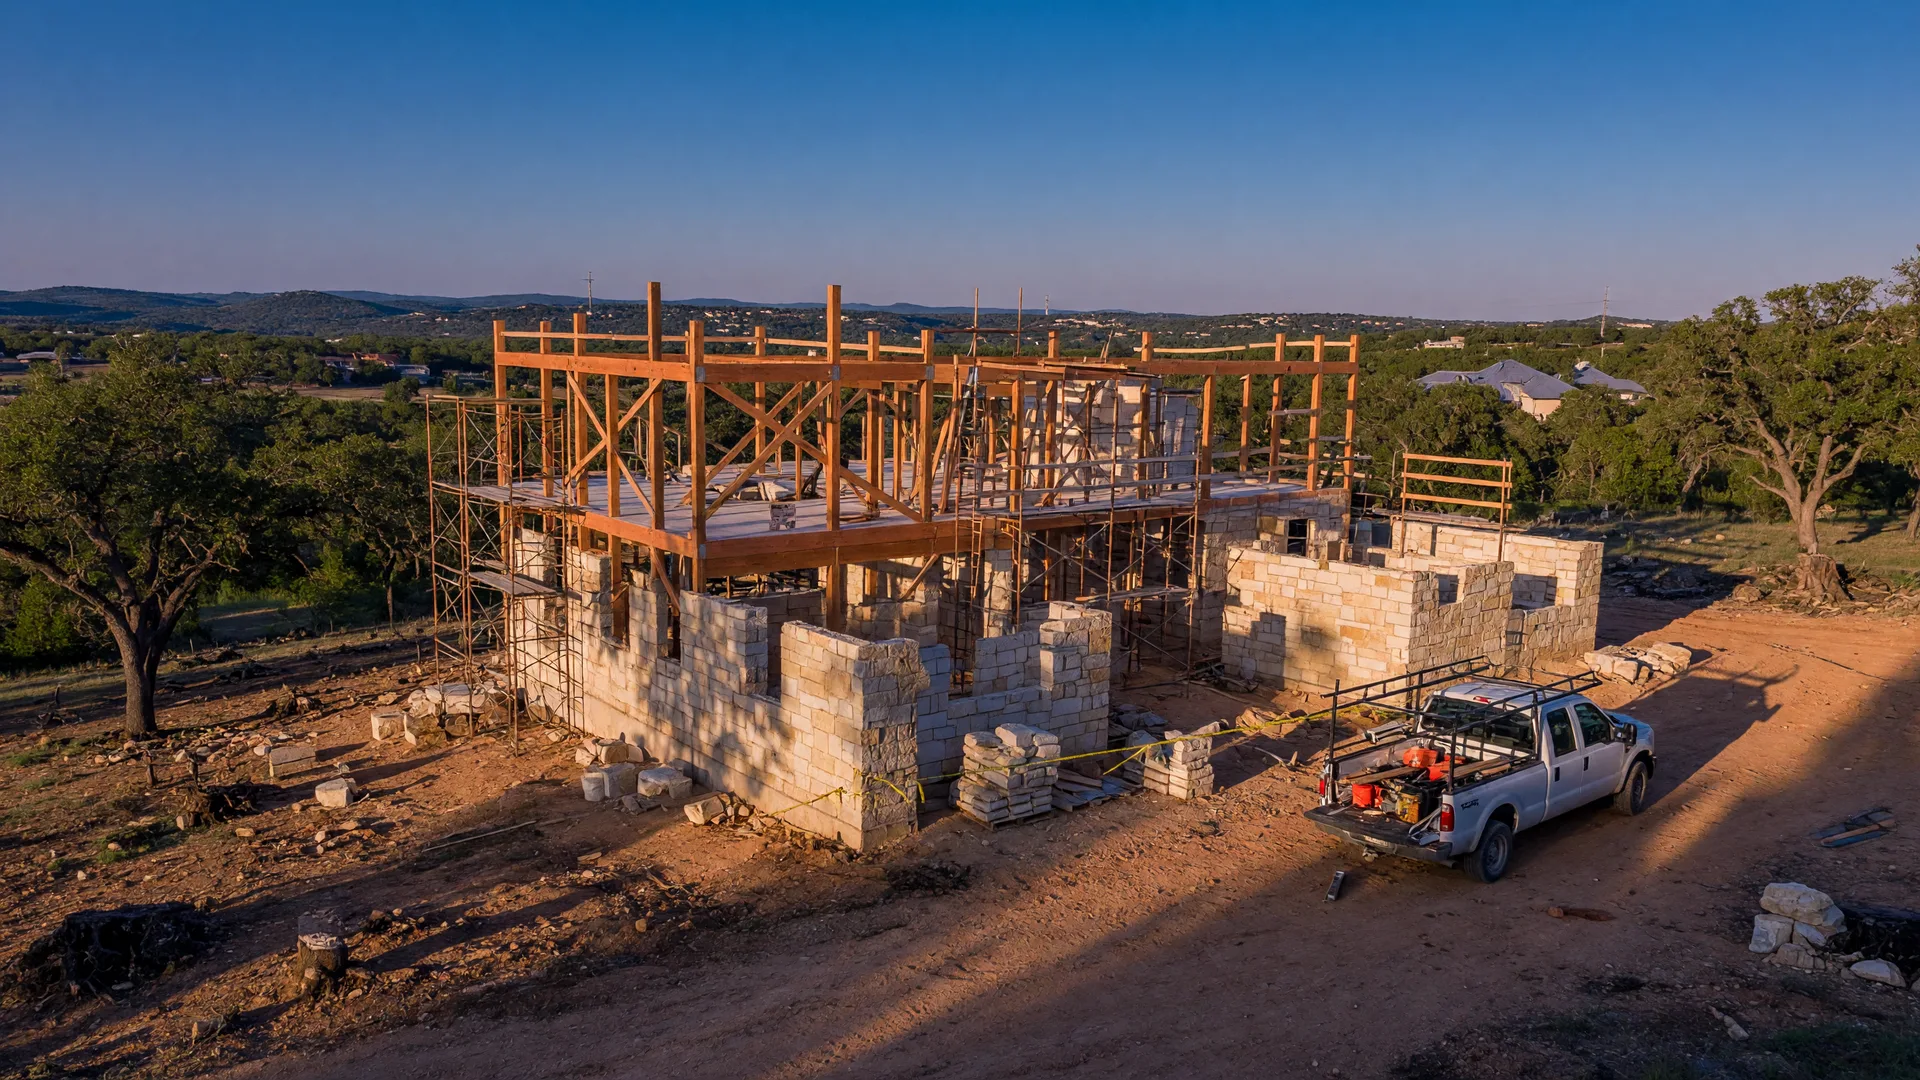
If you want to build rather than buy, the financing question comes first: how do you pay for the construction, and how does that become the mortgage? Construction-to-permanent is the answer that covers both, and the rules below are the verified foundation, cited exactly so you can check them yourself.
One closing or two, your choice
Fannie Mae Selling Guide B5-3.1-01 (06/04/2025) allows construction-to-permanent financing as one closing or as two separate closings. In the one-close version, you sign once and the construction loan automatically converts into the permanent mortgage when the build is done, with the rate and terms set at that first closing. In the two-close version, you close the construction loan first and then refinance into the permanent loan at completion.
Each structure fits a different buyer. One-close is usually the cleaner path for a custom build because the permanent terms are locked up front, but the two-close path gives you a second chance at the market rate at the end. Which one your situation calls for depends on your lot, your builder payment schedule and the lender's construction matrix.
You must hold title to the lot
B5-3.1-01 (06/04/2025) is explicit: the borrower must hold title to the lot. Whether the lot is paid in full or has a lot loan that clears at the construction closing, the borrower has to be on title before the construction financing funds.
What the lender must keep on file
The same rule lists the completion evidence: the lender keeps a Form 1004D, or an acceptable completion alternative, plus a certificate of occupancy or its equivalent. That means the home has to be inspected as complete and legally occupiable before the permanent phase of the loan proceeds, which is why the final inspection date drives the conversion schedule.
What doesn't qualify
B5-3.1-01 (06/04/2025) also draws the boundary: attached condominium units and co-ops are ineligible for construction-to-permanent financing. Detached single-family builds, including a custom home on a Hill Country acreage lot, are the normal use of this product.
The details to verify with your lender
- Maximum LTV, reserves, interest reserve and draw rules: not verified in this pass. Check Fannie Mae B5-3.1-02 and the lender's construction matrix, because these vary by lender and loan program.
- FHA one-time-close: not verified. The check is HUD Handbook 4000.1.
- VA one-time-close: not verified. The check is VA Pamphlet 26-7.
- USDA one-time-close: not verified. The check is USDA HB-1-3555.
The builder side matters too. Before the loan conversation, get a fixed-price build contract, a completion schedule and the builder's license and insurance in hand, because the lender's construction review runs against those documents. The new construction process guide covers the contract and walkthrough sequence in full.
Ready to build? Get pre-approved for the finished house, not the dirt.
I will run the construction-to-permanent structure for your lot and builder contract, so the LTV, reserves and draw plan are real numbers before you sign.
Frequently Asked Questions
What is a construction-to-permanent loan? Tap to expand
Do I need to own the lot before getting a construction-to-permanent loan? Tap to expand
What completion documents does the lender keep? Tap to expand
What property types are ineligible for construction-to-permanent financing? Tap to expand
What construction details should I verify with my lender? Tap to expand
Can I buy land in Spring Branch and build with one loan? Tap to expand
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Mortgage, LLC (NMLS #1660690). He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country.
Full credentials on the About page · Text or call 210-317-6514
Sincerely,
Patrick Kevin Fagan
Fannie Mae rules verified September 25, 2026 against Selling Guide B5-3.1-01 (06/04/2025). Maximum LTV, reserve, interest-reserve and draw rules, and FHA, VA and USDA one-time-close specifics are unverified in this pass; confirm them with your lender and the official program handbooks.
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
