
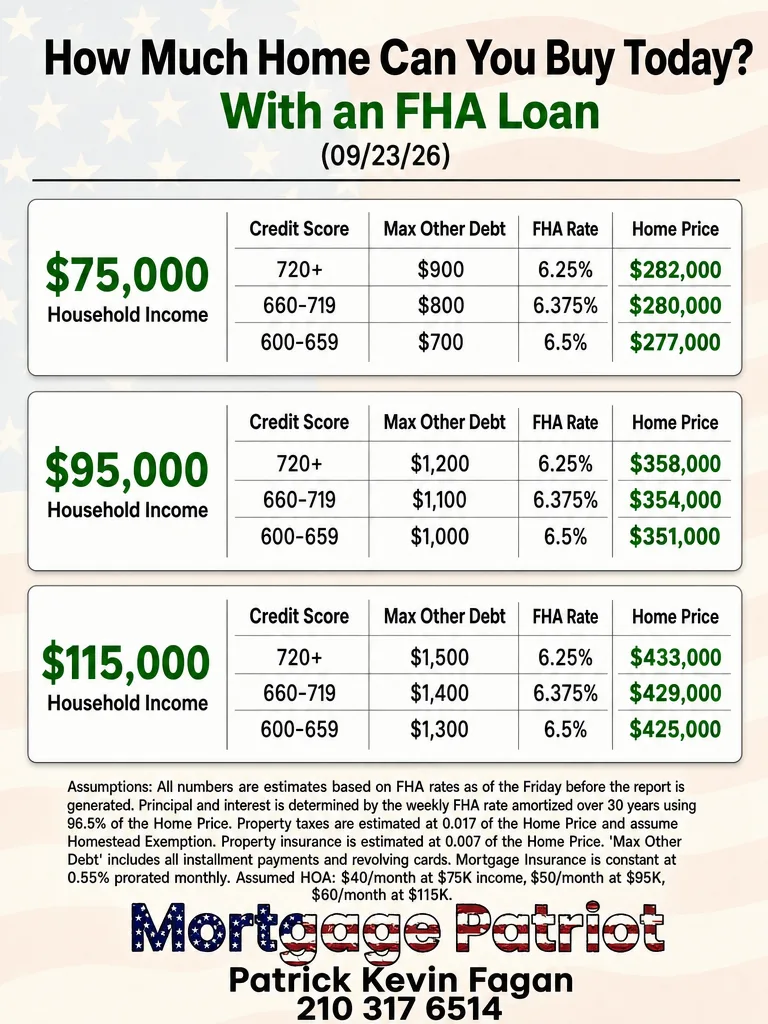
This is the Monday Mortgage Rate Update for the week of October 19, 2026, FHA only. The table below shows the estimated home price each household income tier can support at each credit score tier, based on the most recent FHA rates Patrick texted (as of Friday, September 25, 2026; no new rate text was received for this update). All figures are estimates, and the full assumptions appear in the small print at the bottom of this post.
| Credit Score | Max Other Debt | FHA Rate | Est. Home Price |
|---|---|---|---|
| $75K Household Income | |||
| 720+ | $900/month | 6.25% | $282,000 |
| 660-719 | $800/month | 6.375% | $280,000 |
| 600-659 | $700/month | 6.50% | $277,000 |
| $95K Household Income | |||
| 720+ | $1,200/month | 6.25% | $358,000 |
| 660-719 | $1,100/month | 6.375% | $354,000 |
| 600-659 | $1,000/month | 6.50% | $351,000 |
| $115K Household Income | |||
| 720+ | $1,500/month | 6.25% | $433,000 |
| 660-719 | $1,400/month | 6.375% | $429,000 |
| 600-659 | $1,300/month | 6.50% | $425,000 |
These FHA rates apply at every income tier; the monthly debt limit and the resulting home price vary by income and credit score.
Assumptions: All numbers are estimates based on the most recent FHA rates Patrick texted (Friday, September 25, 2026); no new rate text was received for the week of October 19, 2026. Principal and interest is determined by the weekly FHA rate amortized over 30 years using 96.5% of the Home Price. Property taxes are estimated at 0.017 of the Home Price and assume Homestead Exemption. Property insurance is estimated at 0.007 of the Home Price. 'Max Other Debt' includes all installment payments and revolving cards. Mortgage Insurance is constant at 0.55% prorated monthly. Assumed HOA dues: $40/month at $75K income, $50/month at $95K, $60/month at $115K.
"I help buyers understand exactly what they can afford, step by step, and I am on your side from first showing to closing."
Sincerely, Patrick Kevin Fagan
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
Ready to see the exact number for your income and credit?
Pre-approval gives you the real home price range you can act on, with no guesswork.
Get Pre-ApprovedStart your pre-approval
No hard credit pull or documents to start. Answer a few quick questions and Patrick will personally review your payment and loan options.
