
Patrick's Quick Answer
Yes, a manufactured home on its own land can be financed as real estate, and the rules are verifiable: Fannie Mae B5-2-02 (12/10/2025) requires the home and land to both be legally classified as real property under state law with the loan secured by both, and it allows principal residences, single- or multi-width, plus second homes, multi-width only, with investment properties ineligible. In Texas the catch is the title: manufactured homes are personal property unless the owner elects otherwise through the TDHCA Statement of Ownership process. The property itself must meet Fannie Mae B2-3-02 (02/04/2026), including the HUD Code standard after June 15, 1976, minimum 12-foot width, minimum 400 square feet finished above grade, and the hitch, wheels and axles removed.
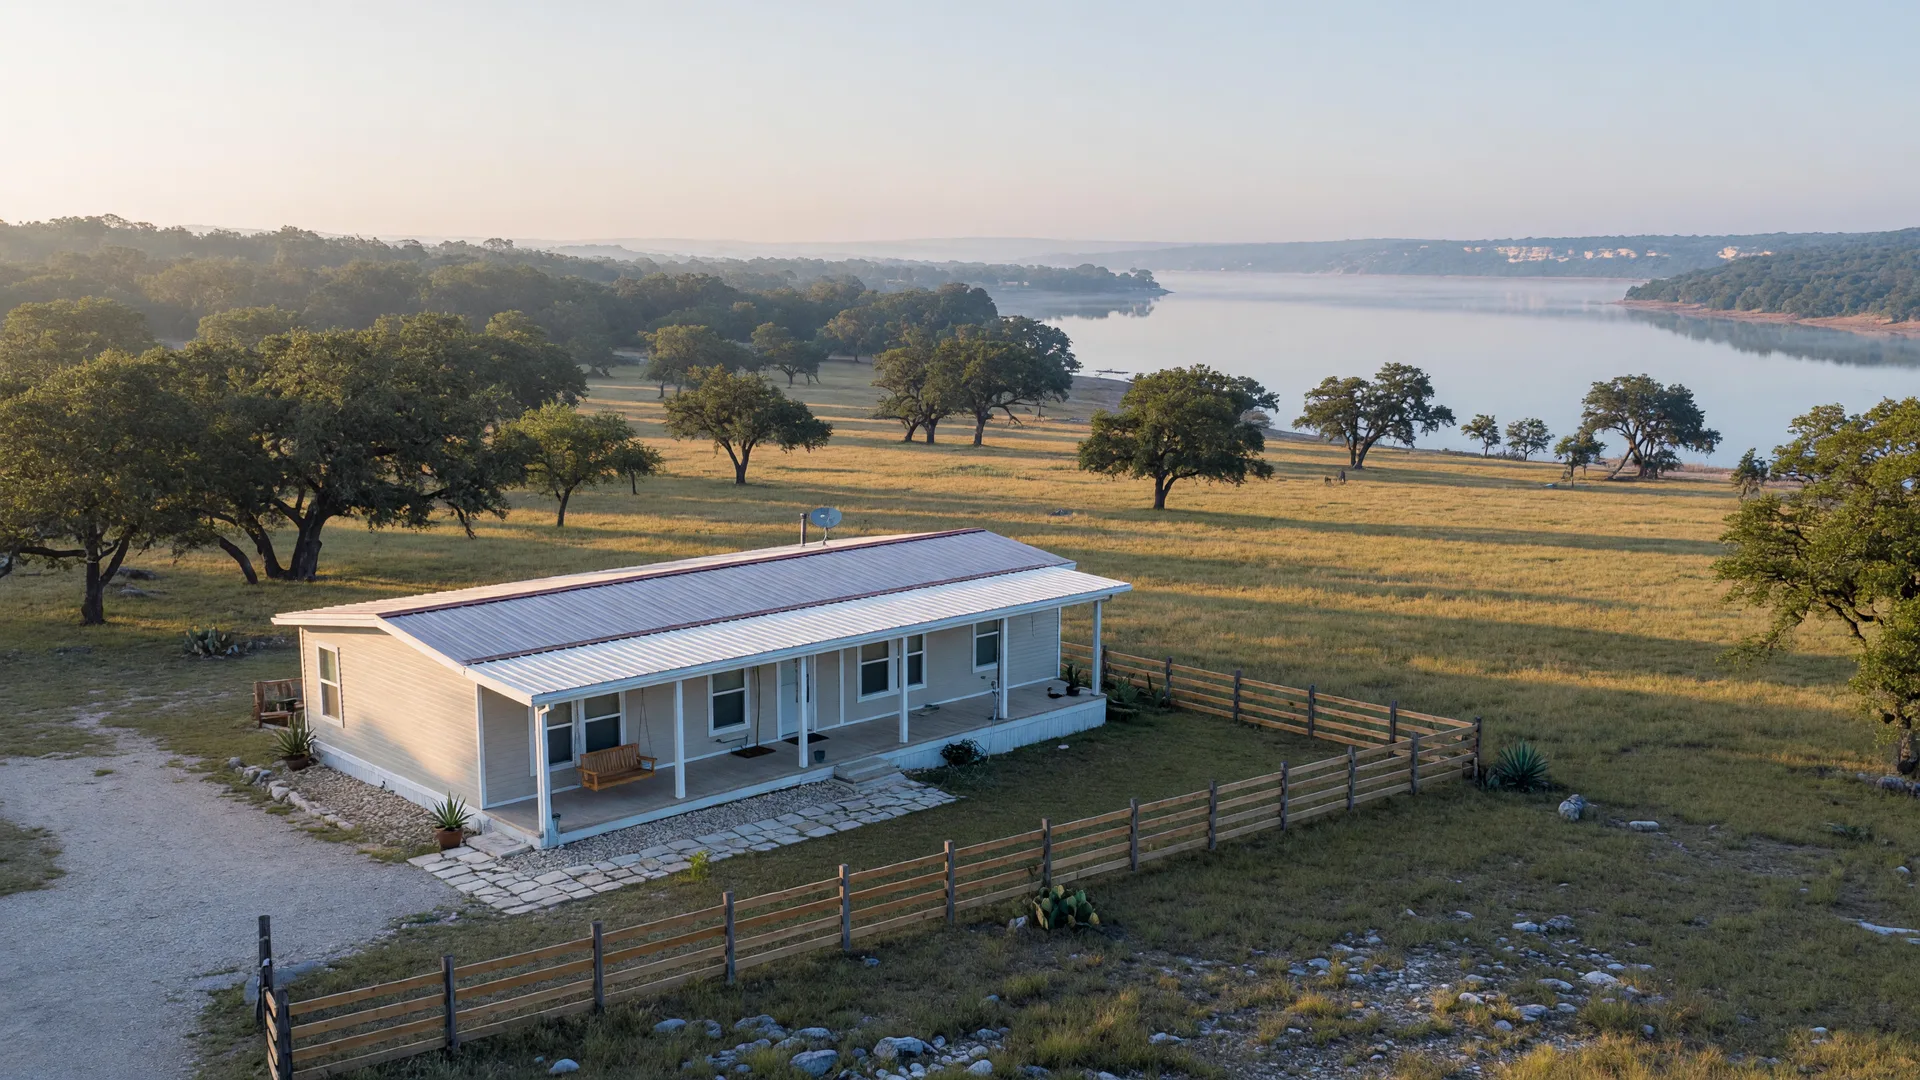
Across Canyon Lake, Spring Branch and Seguin, manufactured homes on acreage are a practical way into a Hill Country property at a lower price point, and lenders do finance them. The financing works exactly like a home mortgage when two things are true: the home is legally real property, and the property meets the agency's physical requirements.
The real property rule
Fannie Mae B5-2-02 (12/10/2025) sets the eligibility frame: the manufactured home and the land must both be legally classified as real property under applicable state law, and the loan must be secured by both. In plain terms, one mortgage covers the home and the dirt together, which is what makes it a true home loan instead of a personal property loan.
The same rule allows principal residences, single- or multi-width, and second homes, multi-width only. Investment properties are ineligible.
The Texas title catch: TDHCA and the Statement of Ownership
In Texas, manufactured homes are titled as personal property unless the owner elects otherwise through the State of Texas Department of Housing and Community Affairs (TDHCA) Manufactured Housing Division's Statement of Ownership process (TDHCA Manufactured Housing Division guide, July 2019). That election is what converts the home to real property attached to the land, which is exactly what the Fannie Mae rule requires. If the home is still titled as personal property, you are financing a vehicle, not a house, and the mortgage options are different.
The property requirements, listed
Fannie Mae B2-3-02 (02/04/2026) spells out what the home itself must be:
- Built to the HUD Code, the federal standard established June 15, 1976.
- Minimum width of 12 feet.
- Minimum 400 square feet of finished above-grade area.
- A HUD Data Plate or HUD Certification Label.
- A permanent chassis and foundation.
- The towing hitch, wheels and axles removed.
- Never previously installed at another site.
The last line matters more than buyers expect: a home that was moved from another site may not qualify, even if it looks great on the new foundation. The placement history is part of the eligibility.
Programs and local permitting
On the help side, TDHCA My First Texas Home lists manufactured homes as an eligible property type in the program matrix dated Aug 17, 2026, so Texas down payment assistance can pair with a manufactured home purchase in the right county. The down payment assistance guide walks how that pairing works.
On the caution side, two things were not verified in this pass. FHA and VA manufactured-home rules live in HUD Handbook 4000.1 and VA Pamphlet 26-7, check those official documents. And county-specific placement permitting in Comal and Guadalupe counties was not verified here, so check each county development office for the address's placement, foundation and occupancy requirements before you commit.
The check-by-address list
- Title status: is the home real property through a TDHCA Statement of Ownership, or still personal property? This decides everything.
- HUD label and Data Plate: confirm both exist and match the home.
- Placement history: has this home ever been installed somewhere else?
- County permitting: call the Comal or Guadalupe County development office for the address.
Want to finance a manufactured home on land?
Send me the address and the placement details, and I will tell you whether the title and property line up for a real mortgage, with the DPA pairing where it fits.
Frequently Asked Questions
Can I get a mortgage for a manufactured home on land in Texas? Tap to expand
What does the TDHCA Statement of Ownership do? Tap to expand
What property requirements does Fannie Mae place on a manufactured home? Tap to expand
Do Texas DPA programs work with manufactured homes? Tap to expand
What should I verify by address before financing a manufactured home? Tap to expand
Can I get an FHA or VA loan on a manufactured home in Canyon Lake? Tap to expand
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Mortgage, LLC (NMLS #1660690). He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country.
Full credentials on the About page · Text or call 210-317-6514
Sincerely,
Patrick Kevin Fagan
Fannie Mae rules verified September 25, 2026 against B5-2-02 (12/10/2025), B2-3-02 (02/04/2026) and the TDHCA program matrix (Aug 17, 2026). FHA and VA manufactured-home rules and county permitting requirements are unverified in this pass; check the official sources and the county development offices.
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
