
Can One Person Be Your Realtor and Your Loan Officer?
Yes. One person, two licensed roles, one coordinated plan from first showing to closing.
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Lending
Yes. Patrick Kevin Fagan is dual licensed in Texas: a real estate sales agent with AXEN Realty LLC (TREC license #454749) and a senior mortgage loan officer with NEXA Lending (individual NMLS ID #877741). One person can show you homes, write your offer, and originate your mortgage, backed by 23+ years in loan origination and 19 years in real estate. He works with buyers throughout Greater San Antonio and the Texas Hill Country, including Bulverde, Spring Branch, Canyon Lake, New Braunfels, Boerne, Schertz, Cibolo, and North San Antonio, and originates home loans statewide across Texas.
The value is coordination with a clear compliance line. Each role keeps its own license, its own rules, and its own disclosures, and this page explains how the two work together and where they stay separate.
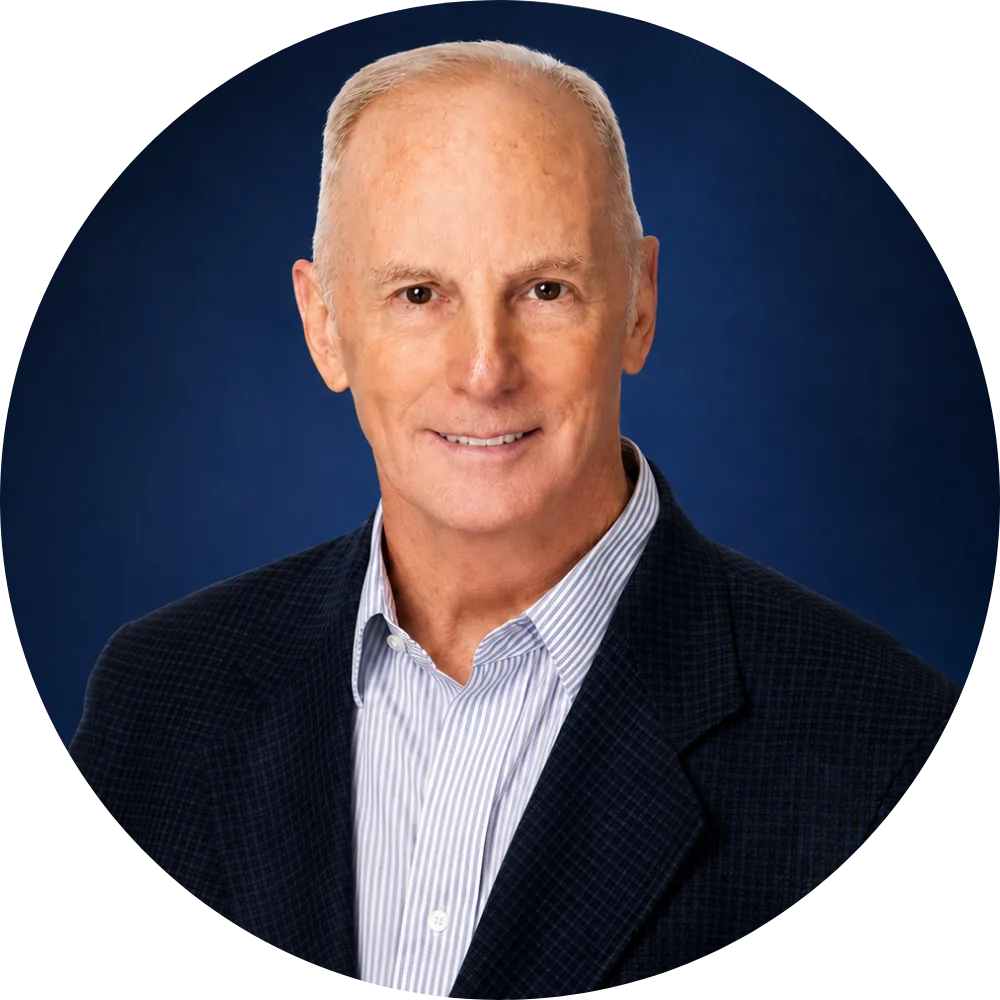
Patrick’s Quick Answer
Yes. Patrick Kevin Fagan (The Mortgage Patriot) is dual licensed in Texas: a REALTOR with AXEN Realty LLC (TREC #454749) and a Senior Mortgage Loan Officer with NEXA Lending (individual NMLS #877741). He brings 23+ years in loan origination and 19 years in real estate, serves buyers throughout Greater San Antonio and the Texas Hill Country including Bulverde, Spring Branch, Canyon Lake, New Braunfels, Boerne, Schertz, Cibolo, and North San Antonio, and originates mortgages statewide across Texas. He specializes in first-time homebuyers, Texas down payment assistance programs such as TSAHC and Home Sweet Texas, and FHA, VA, and conventional loans.
The case for one person on both sides
Why the dual license helps you
The real advantage is not doing two jobs. It is that the buying plan and the financing plan are the same plan. When the person who writes your offer is the person who structured your loan, decisions line up instead of colliding. You also explain your situation once, and the offer, the loan, and the disclosure timelines all come from that one conversation.
Financing-first offers
Pre-approval, loan type, and cash-to-close are known before your offer is written, so the contract matches the loan from the start.
One timeline, one point of contact
Appraisal, inspection, option period, underwriting conditions, and closing deadlines move on one coordinated calendar instead of two separate ones.
Structuring that actually closes
Seller concessions, down payment assistance, and earnest money are written within the limits of your real loan program, not guessed at and discovered at closing.
Plain English on both contracts
The same person explains the purchase contract and the loan documents, so nothing gets lost translating between your agent and your lender.
Built for the buyers who need the most help
First-time buyers and down payment assistance
The buyers Patrick works with most are first-time homebuyers, and the question that matters most to them is simple: how much cash do I need upfront? Because he works on both sides of the transaction, down payment assistance is part of the plan from the first conversation, not an afterthought discovered late in the process.
He specializes in Texas down payment assistance programs such as TSAHC and Home Sweet Texas, and in FHA, VA, and conventional loans. Pre-approval comes first, the loan type is chosen with your goals, and the assistance program is checked against current eligibility rules before any offer is written.
Texas down payment assistance
Programs such as TSAHC and Home Sweet Texas can provide down payment and closing cost assistance to eligible buyers, with income limits and program rules that determine eligibility.
Paired with FHA, VA, or conventional
Patrick works with FHA, VA, and conventional loans and can pair them with the assistance program that fits your situation.
Offer-friendly by design
Concession and assistance limits are loan-program specific. Writing the offer with the loan officer in the room keeps every request inside what underwriting will allow.
One honest note
Assistance program availability, income limits, and terms change, and they vary by loan type and location. Patrick verifies the current rules for your exact scenario during pre-approval rather than assuming a program will be there on closing day.
The same person, four clear stages
How it works from offer to closing
Each stage uses one of the two licenses, and both stay on the same calendar. Nothing here is a rate or a guarantee; it is the order of work and where each role carries the process.
1. Pre-approval
In the loan officer role, Patrick reviews your credit, income, and assets, helps you choose between FHA, VA, and conventional loans, checks whether Texas down payment assistance fits, and issues your pre-approval and Loan Estimate.
2. The offer
In the agent role, Patrick writes the offer with the financing already known: option period, earnest money, and any concession request are set inside the limits of your actual loan and assistance program, then negotiated on your side.
3. Under contract
Both roles track one calendar: inspection and repair negotiations, appraisal, title work, option period deadlines, and underwriting conditions all line up so nothing waits on a phone call between two offices.
4. Closing
The Closing Disclosure is reviewed against the Loan Estimate, funds to close are confirmed, the final walkthrough happens, and title, funding, and keys follow. One person stays accountable for the whole path.
Where the two roles stay separate
Compliance and transparency
Dual licensed does not mean one combined permission slip. The agent role and the loan officer role are separate careers with separate regulators, separate rules, and separate disclosures. That separation is what makes the arrangement safe for you, and Patrick treats it as a feature, not a loophole.
Two licenses, two regulators
The real estate license is issued and regulated by the Texas Real Estate Commission (TREC). The mortgage license is registered through NMLS and regulated by the Texas Department of Savings and Mortgage Lending, with federal consumer protections under RESPA, TILA, the Equal Credit Opportunity Act, and the Fair Housing Act.
No referral fees, no steering
Federal law (RESPA) prohibits referral fees and kickbacks for steering you to a lender. When one person holds both roles, that separation still holds: the loan is offered on its merits, the roles are disclosed, and the choice is yours.
Disclosures you can count on
Agent side: agency disclosure and your written representation agreement. Loan side: a Loan Estimate after application and a Closing Disclosure before closing. Both roles are disclosed to you in plain terms, and you always choose which lender and which agent you work with.
Licenses you can verify
Both credentials are public records. Verify TREC #454749 at the Texas Real Estate Commission and NMLS #877741 on NMLS Consumer Access before you hire anyone.
A fair question, answered straight
Does using one person for both change what the loan costs? No. The fees your lender charges and the rate on your Loan Estimate come from the loan program and the market, not from having one person on both sides. The benefit is coordination, education, and an offer written around your real financing. Compare the numbers as you would with any lender, and if you prefer a separate agent and lender, that works too. Patrick’s job in either setup is to keep you informed and on your side.
Verify the credentials yourself: Texas Real Estate Commission (TREC #454749) and NMLS Consumer Access (NMLS #877741).
Common questions
Realtor and loan officer, in one person?
The questions buyers ask most often about the dual license.
Can the same person really be my realtor and my loan officer? +
Yes. Patrick Kevin Fagan is dual licensed in Texas: a real estate sales agent with AXEN Realty LLC (TREC #454749) and a senior mortgage loan officer with NEXA Lending (individual NMLS #877741). He brings 23+ years in loan origination and 19 years in real estate, and he works with buyers across Greater San Antonio and the Texas Hill Country, originating mortgages statewide across Texas.
Is there a conflict of interest when one person does both? +
The two roles are licensed separately and regulated separately. Real estate work falls under the Texas Real Estate Commission (TREC), while mortgage work is registered through NMLS and regulated by the Texas Department of Savings and Mortgage Lending, with federal consumer protections under RESPA, TILA, the Equal Credit Opportunity Act, and the Fair Housing Act. Referral fee arrangements are prohibited, and you always choose the lender you use.
Does using one person for both save money on closing costs? +
It can help structure your purchase to reduce cash to close, because seller concessions and down payment assistance are written within the limits of your actual loan program rather than guessed at late. It does not change the fees your lender charges, so you should still compare the Loan Estimate as you would with any lender.
What does dual licensed mean in Texas? +
It means one person holds both a Texas real estate sales agent license (TREC #454749, with broker AXEN Realty LLC) and a mortgage loan originator license (NMLS #877741, with NEXA Lending). Each role keeps its own license, its own rules, and its own disclosures.
Do I have to work with Patrick for both roles? +
No. You can use a separate agent and a separate lender if you prefer. The advantage of one person for both is coordination: the offer, the financing, and the closing timeline come from the same plan. Patrick will also coordinate with the agent or lender you choose.
Where does Patrick work as a realtor and as a loan officer? +
For real estate, he serves Greater San Antonio and the Texas Hill Country, including Bulverde, Spring Branch, Canyon Lake, New Braunfels, Boerne, Schertz, Cibolo, and North San Antonio. For mortgages, he can originate home financing statewide across Texas.
Is it worth it to bundle my realtor and lender? +
It can be, and it can also be wrong for your specific deal, so the honest answer is: compare. The value of one person for both roles is coordination, the offer structure, the financing, and the closing timeline come from the same plan, which matters when seller concessions, down payment assistance, and rate locks all have to line up. The value only holds if the numbers hold: you still have the right to choose your own lender, and you should compare the Loan Estimate you would get separately. When the bundled numbers match or beat the separate quotes, the coordination is pure upside.
Do I have to find an agent before working with a lender? +
No, and for many buyers the better order is lender first. A dated pre-approval tells you the price range and payment before you tour, and it makes every offer you write stronger. The two roles are licensed separately, agent work under the Texas Real Estate Commission (TREC) and mortgage work through NMLS with the Texas Department of Savings and Mortgage Lending, and you never need one license to engage the other.
Is it a conflict of interest if my realtor is also my loan officer? +
The two roles are regulated separately, and the consumer protections exist on both sides: real estate sales under TREC and the Texas REALTORS rules, and mortgage origination under NMLS with RESPA, TILA, and the Equal Credit Opportunity Act, all dated federal and state authority. Referral-fee arrangements that would push a deal for the agent's benefit are prohibited, and the consumer always chooses the lender. The check that keeps it honest is the same as with any professional: review the compensation disclosures, compare a separate quote, and walk if anything is not disclosed in writing.
Buying new construction? See the incentives before you sign.
Builders are advertising rates from about 3.4% to 4.99% in a 7% market. Patrick decodes each offer and compares it against outside financing.
Get both roles working from the same plan
Start with a free discovery call. Patrick will review your goals, your financing options, and any Texas down payment assistance you may qualify for, whether you hire him for one role or both.
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Lending. He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country, and originates home loans statewide across Texas. He specializes in first-time homebuyers, Texas down payment assistance (TSAHC, Home Sweet Texas), and FHA, VA, and conventional loans.
