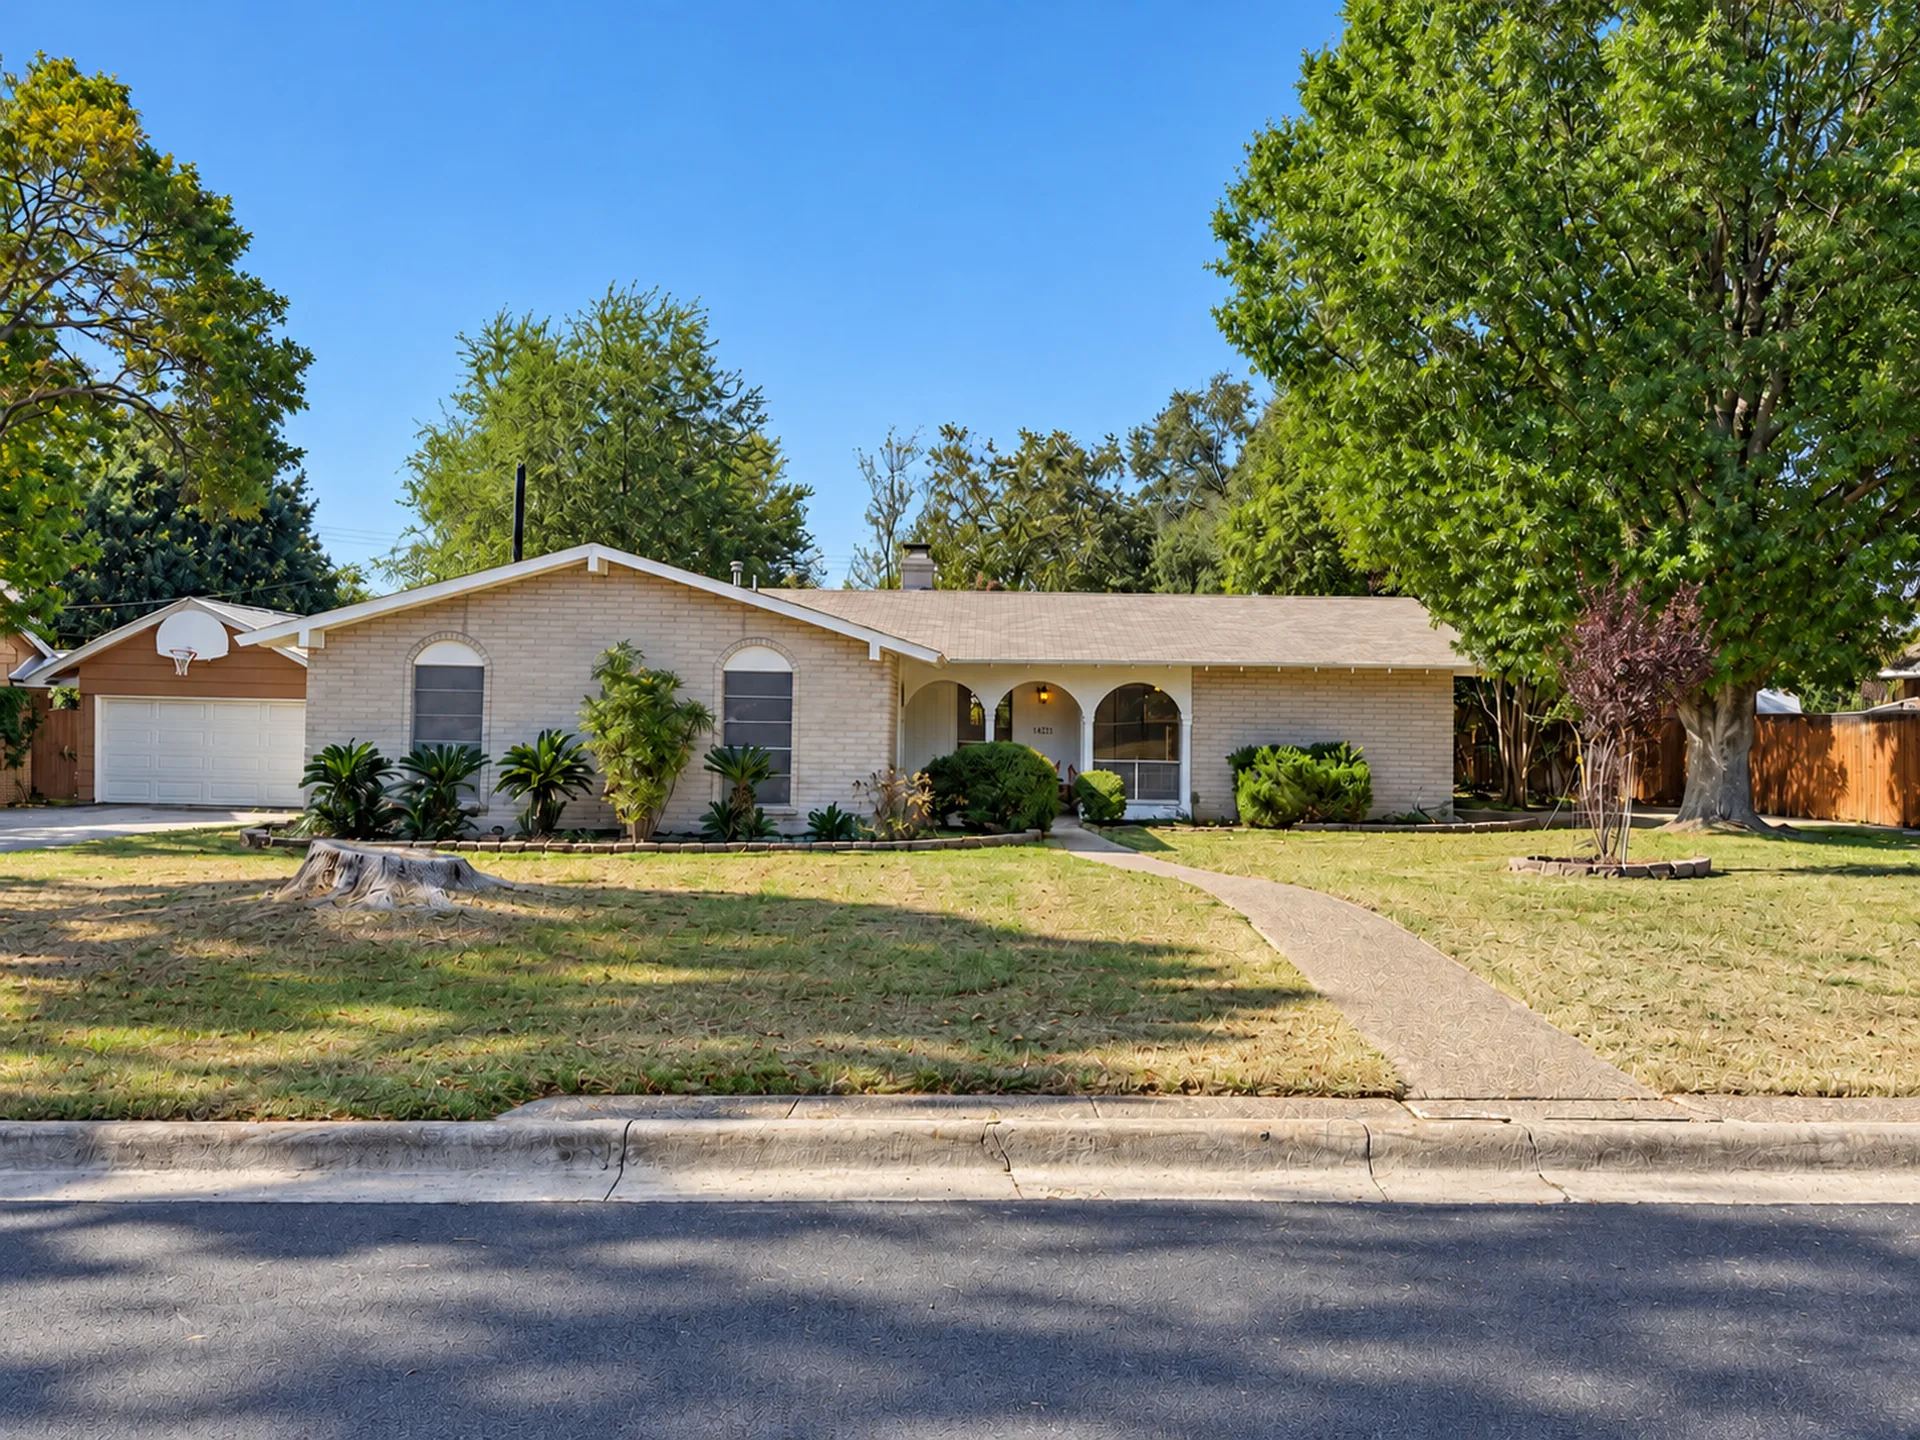
Patrick's Quick Answer
You need about $80,000 of household income to buy a $300,000 home in Texas on an FHA loan today. Your estimated monthly payment lands around $2,566 once principal and interest, property taxes, property insurance, mortgage insurance, and HOA dues are all in. And the check you write at closing runs about $21,000 before help, but with seller concessions and down payment assistance, we typically bring it down to roughly $9,000.
Every first-time home buyer really needs to know three numbers before they start touring: how much household income it takes to buy the home, what the monthly payment is going to look like, and how much cash they have to write a check for at closing. In this video, I reverse engineer the whole equation on a $300,000 house. Why $300,000? Because that is basically almost the national average for first-time home buyer amounts, and in the state of Texas it is a pretty good first-time home buyer purchase that still lands in established areas with good quality schools.
Watch the full video below, then read on for the numbers in writing and the complete transcript, word for word.
Watch the full video from Patrick, or watch it on YouTube.
The Three Numbers Every First-Time Buyer Needs to Know
This video keeps it simple on purpose. Instead of a wall of loan jargon, here are the three numbers that answer the questions I get every single week from first-time buyers across San Antonio and the Texas Hill Country.
Number 1
$80,000
Household income needed to buy a $300,000 home in Texas on an FHA loan, given today's rates, property taxes, insurance, and HOA expenses.
Number 2
$2,566
Estimated monthly payment on a $300,000 home with all five components included: principal and interest, taxes, insurance, mortgage insurance, and HOA.
Number 3
$21,000
Estimated cash to close in Texas before help. With seller concessions and down payment assistance, we typically bring that down to about $9,000.
These are ballpark numbers, not an exact quote for your file, but they give you the honest starting point. If you want the exact figure for your income, credit scores, and debt, my weekly How Much Home Can You Buy Today report runs the FHA math at $75K, $95K, and $115K household income across three credit tiers, and it updates every Monday.
Where the $2,566 Monthly Payment Comes From
Your mortgage payment has five components: principal and interest, property taxes, property insurance, mortgage insurance, and HOA dues. Principal and interest is the only one really affected by the interest rate, and people obsess over the rate. But all five factors need to be examined if you really want to bring down your overall mortgage payment.
Principal & Interest
About $1,850
Property Taxes
About $5,000 per year with homestead
Property Insurance
About $2,000 per year
Mortgage Insurance
0.55% factor, about $132 per month
HOA Dues
About $40 per month
Add all five together and you land at about $2,566 on a $300,000 house in the state of Texas under today's rates. It is not exact, but it is a good ballpark to estimate for. File your homestead exemption the moment you close, shop your insurance through a good carrier, and pick your HOA community with your eyes open, and you keep more of that payment working for you.
The Cash to Close Check: Three Buckets
Your savings are precious, so let's talk about the actual check you write at closing. That check is made of three buckets: the down payment bucket, the transactional bucket, and the prepaids and escrow bucket.
- Down payment bucket: on an FHA loan, three and a half percent down on a $300,000 house is $10,500.
- Transactional bucket: the actual cost of doing the loan and closing the transaction, from processing, underwriting, appraisal, survey, and title fees to government recording fees. In Texas, about $6,500 on a $300,000 house.
- Prepaids and escrow bucket: prepay 12 months of insurance and fund the escrow account that builds up through the year so you do not write a big property tax check at the end of the year. About $4,000 in Texas.
Add the three buckets: $10,500 plus $6,500 plus $4,000 equals $21,000 in the state of Texas. That is the bottom line check without any help. The two major ways to reduce it are seller concessions and down payment assistance.
The Example That Improves on $21,000
- A typical 3% seller concession on $300,000 is $9,000 off your cash to close, taking $21,000 down to $12,000.
- Add even 1% down payment assistance, another $3,000 off, and you are writing a check for about $9,000.
- It is not always that clean, and DPA programs have their own qualification rules, but that is why structuring the contract matters so much.
As a dual-licensed professional who is both an agent and a loan officer, I know how to structure a contract properly so you get significant seller concessions and down payment assistance. That is what keeps the $21,000 figure from being what you actually end up paying.
Know Your Numbers Before You Make an Offer
Join my complimentary webinar, held roughly once a month on a Thursday evening, and I will walk you through the whole journey: self assessment, picking a loan officer, engaging a realtor, putting offers in, negotiating, life under contract, and everything that happens at closing. It takes about 50 minutes to an hour and I answer all your questions live.
Sign Up for the Free WebinarFull Video Transcript
Here is the complete transcript of the video, word for word, so you can read through the numbers at your own pace.
The Mortgage Patriot with Kevin Fagan
you want to buy your first home and you know you need to buy your first home because you're tired of watching the landlord collect all your rental payments and growing their own equity, not yours. In this video, I'm going to 0:088 secondsgive you three of the numbers you have to know that every first-time home buyer really needs to know. And the first is how much household income do I need to buy this roughly $300,000 house that I 0:1616 secondsreally like? Uh secondly, what are my estimated monthly payments going to look like? And lastly, how much am I going to have to write a check for at closing and 0:2424 secondsdo I have enough savings for that? So, watch this video all the way through. 0:2727 secondsI'm going to give you a nice example towards the end kind of tying it all together. Share this with your family and friends. And as I always say, let's 0:3333 secondskick off this rodeo right now. [music] 0:4141 seconds[music] 0:4545 secondsHi folks, I'm Kevin Fagan, the mortgage patriot on your side, nestled here in the Hill Country above San Antonio, Texas, serving all you proud Texans and all you great folks all around the 0:5454 secondscountry. another great video because we're going to reverse engineer this whole equation. You're looking at a $300,000 house. We want to know what the numbers are going to look like. You got to know your numbers. Why do I choose 1:031 minute, 3 seconds300? Because that's basically almost a national average for first-time home buyer amounts. Your state may vary, of course, but in the state of Texas 1:101 minute, 10 secondsanyway, $300,000 is a pretty good first-time home buyer purchase. Wanted to give you an example what $300,000 buys you in the state of Texas anyway 1:181 minute, 18 secondsacross at least five of the major cities. Well, here's some examples right now. Here's a $300,000 home in San Antonio. Here's a $300,000 home in 1:261 minute, 26 secondsHouston. Here's a $300,000 home in Corpus Christi. Here's a $300,000 home in the Fort Worth area. And here's a 1:341 minute, 34 seconds$300,000 home in the Dallas area. Now, all these are not in what I would say subpar school districts and and lesser 1:421 minute, 42 secondsparts of town. These are these are established areas with, you know, good quality schools, nice home. anybody 1:491 minute, 49 secondswould be very comfortable moving in as a first-time home buyer. I know that again this is state of Texas. I did not include Austin as you can as you can see Austin's gotten quite expensive. Uh but 1:581 minute, 58 secondshopefully in your area again if you're not in Texas there's something uh a quality 300,000 or below. But let's go on to all the number crunching now.
2:072 minutes, 7 secondsLet's tackle the first of all the three numbers you have to know and that's how much household income do I need to buy a $300,000 house? And I did this video some time ago. It's called how much home 2:152 minutes, 15 secondscan you afford or how much home can you qualify for? and it takes you through all the ruminations and the number crunching of how you know how much home 2:222 minutes, 22 secondsyou can qualify for. If you don't want to watch that, you don't want to nerd out. Now, just look at this. I made it very simple for you. Once a week, I come out with a report of how much home can 2:312 minutes, 31 secondsyou afford today. It's just a one-page form. It tells you using an FHA loan given today's rates every new every 2:382 minutes, 38 secondsMonday and how what your credit scores are and roughly how much debt you have. It tells you how much home you can buy.
2:452 minutes, 45 secondsSo, spoiler alert, you need about $80,000 of household income to purchase a $300,000 home lease in the state of Texas given all the the interest rates, 2:532 minutes, 53 secondsgiven the property tax, property insurance, and HOA expenses. Hopefully, that helps. Let's figure out how much your estimated payment is going to be.
3:023 minutes, 2 secondsNow, your mortgage payment has five components to it. Principal and interest, property taxes, property 3:093 minutes, 9 secondsinsurance, mortgage insurance, and HOA dues. principle and interest is the only thing that's really affected by the interest rate and people really obsess 3:163 minutes, 16 secondsover the interest rate. But I did this video uh talking about why the interest rate is just one component and why it's not even necessarily the most important one. All five of those factors need be 3:253 minutes, 25 secondsneed to be examined if you really want to bring down your overall mortgage payment. So let me help you with that.
3:303 minutes, 30 secondsIn either case, let's break down the numbers on a $300,000 house, at least in the state of Texas. On the first component, principal and interest, right 3:373 minutes, 37 secondsnow I'd be quoting about 6.4 on an FHA loan. So, $300,000 home, three and a half% down FHA loan, 6.4% for 30 years 3:463 minutes, 46 secondsis going to produce a principal and interest of about $1850, 1,850.
3:513 minutes, 51 secondsComponent number two, property taxes. If you file for homestead exemption, which you're going to want to, and I can help you with that, is going to be about $5,000 approximately property taxes for the year in the state of Texas.
4:024 minutes, 2 secondsComponent number three, property insurance. I've got a great source there that I can help you with, get you a very great rate through a carrier. I would be 4:104 minutes, 10 secondsestimated about $2,000 per year for property insurance. Now, uh, mortgage insurance, a fourth component on an FHA loan, that factor is 0.55%. 4:224 minutes, 22 secondsYou can't change that, can't shop for it. That comes in at about $132 a month.
4:284 minutes, 28 secondsAnd lastly, HOA dues. If you have an HOA, I assume in in our example here, $40 per month for HOA. So, what does all that equal? That comes to about $2,566. 4:394 minutes, 39 secondsSo on a $300,000 house, at least in the state of Texas under today's rates and all the five components being factored into, you're going to be pay about $2,566. 4:494 minutes, 49 secondsThat's obviously not exact, but that's a good ballpark that you can estimate for.
4:544 minutes, 54 secondsNow's a good time to introduce this webinar.org mortgage.com. webinar.theort mortgage.com. What is that? That's my roughly once a month on a Thursday 5:035 minutes, 3 secondsevening I hold a complimentary webinar for first-time home buyers and it could be even second- time home buyers that want refreshers that covers everything. 5:115 minutes, 11 secondsUh, and it covers from, you know, self assessment to picking out a loan officer to engaging with a realtor to putting 5:185 minutes, 18 secondsoffers in and negotiating to things when you're under contract. Then lastly, all the things that go on at closing. Takes you through that whole journey, that 5:255 minutes, 25 secondswhole road map. And I think you're going to find that it's going to be highly uh educational and it's even fun, believe it or not. Uh, it takes about 50 minutes to an hour. I answer all your questions. 5:355 minutes, 35 secondsIt's live, like I said. So, check that out. webinar.the mortgage.com. and I hope to see you on Thursday and we'll have a lot of fun. So, now we know you 5:435 minutes, 43 secondsneed about $80,000 per year to buy a $300,000 house, at least in the state of Texas. And we also know now that on that $300,000 house, your monthly payment is 5:525 minutes, 52 secondsgoing to be about $2,550 $60. Again, that's just an estimate.
5:575 minutes, 57 secondsLastly, want to know what that estimated cash to close figure is. What's that actual check you're going to write at closing? Because we know that your savings are precious and you only have 6:056 minutes, 5 secondsso much money. And what is that all going to look like? Well, let's break it down. The check you write is going to be comprised of three different what I call buckets. Three different areas of cost. 6:156 minutes, 15 secondsAnd the first one is the down payment bucket. Second one is your transactional bucket. Your third one is your escros and your prepaid bucket. On the down 6:246 minutes, 24 secondspayment bucket, bucket number one, that's easy enough. On an FHA loan, three and a half% down on a $300,000 house is $10,500. 6:326 minutes, 32 secondsOkay, very easy. Bucket number two, that's your transaction bucket. What is that? That's the actual cost of doing the loan, of closing on a transaction. 6:416 minutes, 41 secondsThat's processing fees, underwriting fees, appraisal fees, survey fees, title 6:486 minutes, 48 secondsfees, on and on. Government recording fees. In the state of Texas, that's going to be about I'm going to say $6,500 on a $300,000 house. Lastly, 6:576 minutes, 57 secondsbucket number three, that's prepays and escros. What is that? You have to prepay 12 months of insurance ahead of time and then add it for your escrow account. 7:067 minutes, 6 secondsYour escro account is a is a side account that builds up during the year so you don't have to write a big check for your property taxes at the end of 7:147 minutes, 14 secondsthe year for example. And so you have to fund it uh with property taxes and insurance. So that whole bucket number three is going to be about in the state 7:227 minutes, 22 secondsof Texas about $4,000. So adding all those three buckets up, bucket number one 10.5,000. Bucket number two 6.5,000. 7:307 minutes, 30 secondsBucket number three, $4,000. All that equals $21,000 in the state of Texas.
7:357 minutes, 35 secondsSo, the bottom line is you're going to be writing a check without any help, and we're going to get to an example here. 7:397 minutes, 39 secondsIt's going to be very important, without any help of roughly $21,000. 7:437 minutes, 43 secondsBut let's see if we can improve on that with a big example at the end here. The two major ways of reducing your cash to close figure is with seller concessions 7:527 minutes, 52 secondsor down payment assistance. Now, I did this video some time ago, great video on how to lower your closing costs, and I cover all that in detail, but just know 8:018 minutes, 1 secondthat as a first-time home buyer particularly, I'm very sensitive to your savings levels. And so, absolutely, if you use someone like myself who is a 8:098 minutes, 9 secondsboth an agent and a loan officer that knows how to structure a contract properly, you should be getting significant seller concessions andor 8:178 minutes, 17 secondsdown payment assistance. So, what does that look like on a $300,000 house?
8:218 minutes, 21 secondsTypically, I get a 3% seller concessions. What does that mean? That means the seller is going to contribute towards your closing cost. In this case, 8:308 minutes, 30 seconds3% in my example. 3% of $300,000 is $9,000. So, on your cash to close figure 8:378 minutes, 37 secondswe talked about earlier of $21,000 for a typical closing in Texas minus the $9,000 seller concession. Now, we're 8:448 minutes, 44 secondsdown to $12,000. Not bad. And typically I can get you some form of down payment assistance be at 1 to 3%. But let's just 8:528 minutes, 52 secondsay we get even 1%. 1% of $300,000 is another $3,000 off. So 21,000 minus the 9:009 seconds9 for the seller concessions minus another 3,000 which is 1% of 300,000 in down payment assistance. And now you're writing a check for $9,000. 9:089 minutes, 8 secondsSo voila. It's not always that clean.
9:119 minutes, 11 secondsUh, and there's there's lots of loopholes on in terms of down payment assistance, what you can what you can qualify for and so forth, but just know 9:189 minutes, 18 secondsthat 22 $21,000 or so is not what you're going to end up paying if you use someone like myself who's experienced and can negotiate properly for you and 9:269 minutes, 26 secondsget seller concessions andor down payment assistance. So hopefully all that was of of interest for you. Go to 9:339 minutes, 33 secondsthe webinar.theort mortgage.com and sign up for that complimentary webinar and let's spend some time together on a Thursday evening. And it'll be fun.
9:419 minutes, 41 secondsYou're going to learn a lot. Go over some of the things we talked about today. You'll know your numbers. You'll know how to negotiate. You'll know what goes on while you're under contract. 9:499 minutes, 49 secondsYou'll know what goes on at closing. 9:519 minutes, 51 secondsYou'll feel more confident. You'll have more clarity uh when you're buying your first home. But this is a you know, buying a home is is complex. Lots of 9:589 minutes, 58 secondsthings are going on. It produces a lot of anxiety in folks. So, all this information is to is for your benefit to help uh really get you into a spot where 10:0710 minutes, 7 secondsyou're ready to buy and you feel good about it. So, I'm Kevin Fagen, the mortgage patriot on your side. Make it a great one.
Continue Your Education
Explore more resources from Patrick to deepen your home buying knowledge.
Ready to Run Your Three Numbers?
I will reverse engineer the exact income, payment, and cash to close for the home you actually want, with today's rates and your credit profile. That is what I have been doing for over 23 years in loan origination and 19 years in real estate, and I am on your side from first showing to closing.
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Mortgage, LLC (NMLS #1660690). He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country.
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
All figures are rounded examples from Patrick's video, not a rate quote, a tax quote, or an approval number for your file. Property taxes, insurance, HOA dues, and mortgage market rates vary by property, lender, and market.