
Patrick's Quick Answer
Financing a barndominium works when the property works as a home, because none of the agency guides, Fannie Mae, VA Pamphlet 26-7 Chapter 12 or the USDA site requirements, have a separate barndominium category. The real test is standard property eligibility plus the appraiser's support of value: Fannie Mae B4-1.3-04 says the property should be generally conforming and acceptable in the market area. Build one the typical way, construction-to-permanent, and the details on that route are on the construction-to-permanent loan page. Agency-specific barndominium rules and appraisal comparable standards were not verified in this pass, so check with the lender's underwriting.
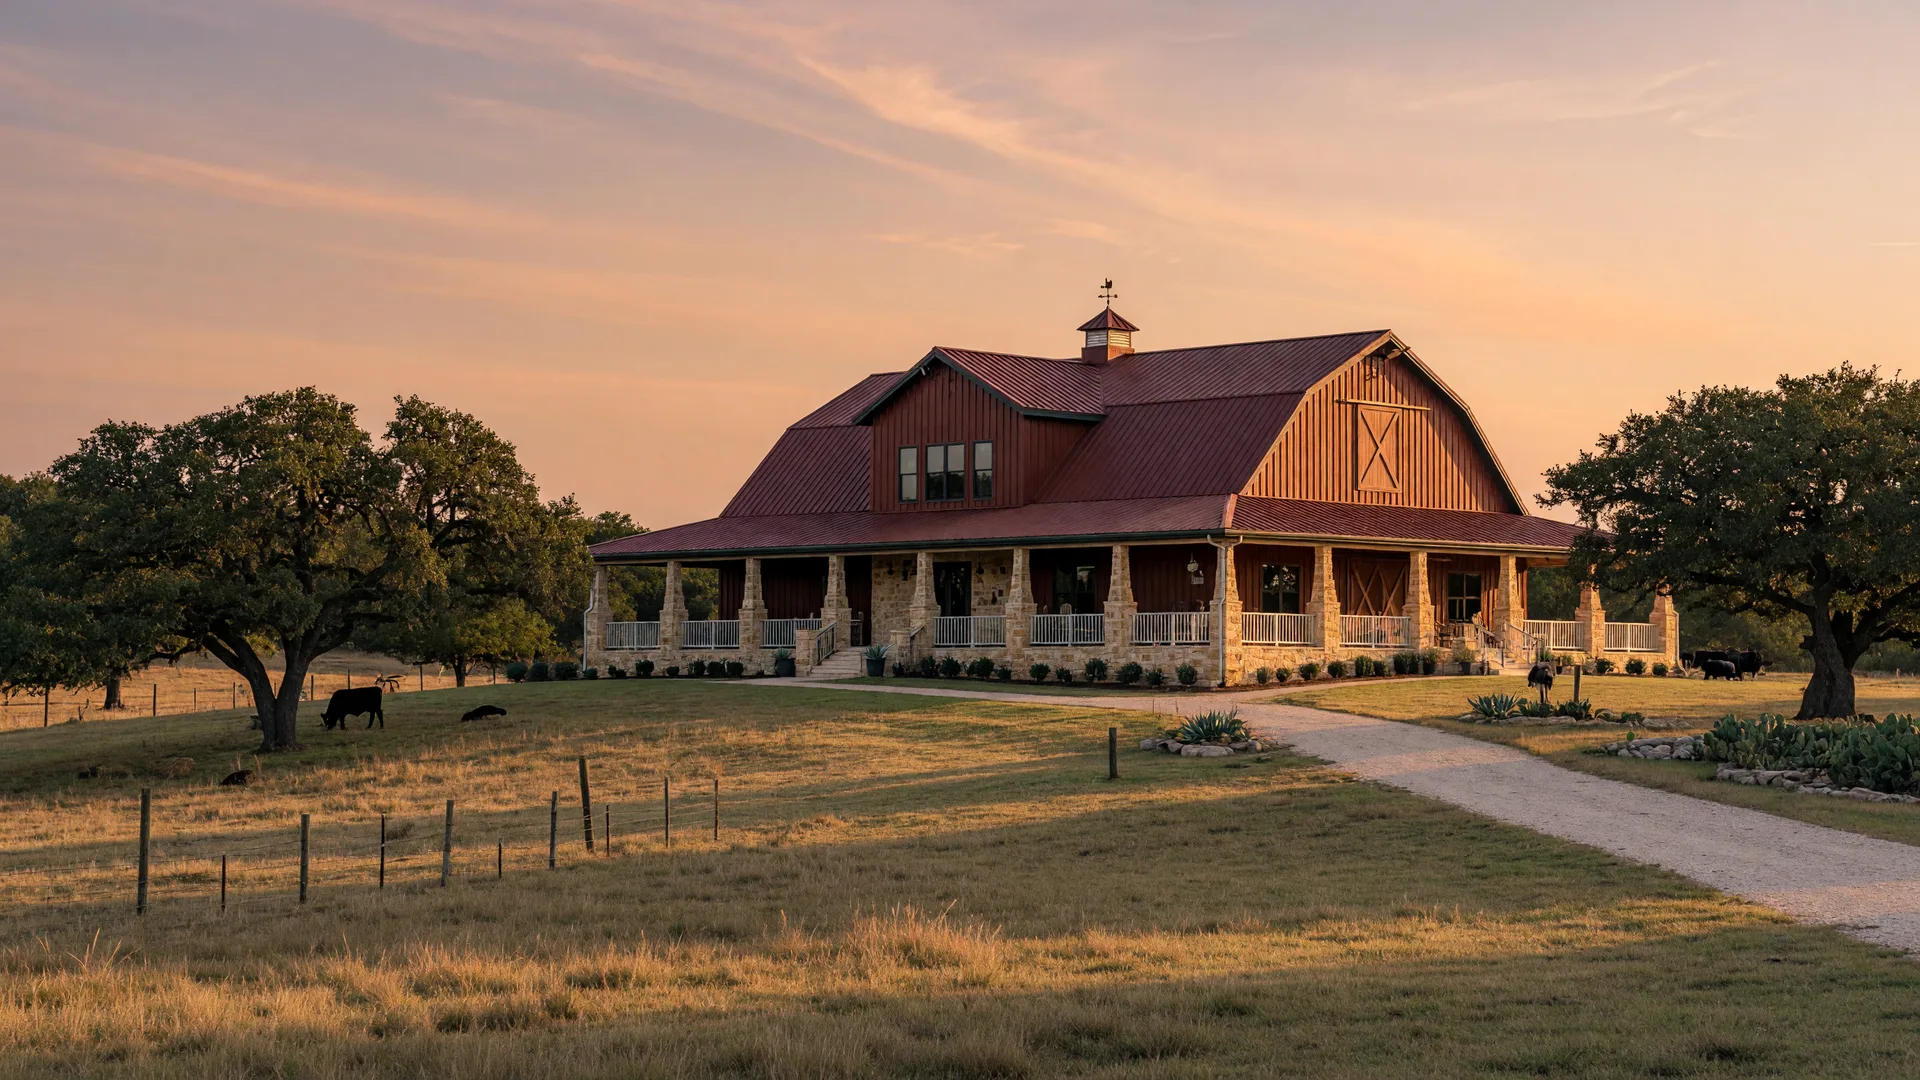
Barndominiums are everywhere in the Texas Hill Country, and every one of them raises the same financing question before anyone signs. The honest answer starts with a fact that surprises most buyers: no agency guide has a barndominium checkbox. Here is what the rules actually say, and what determines whether yours finances.
There is no barndominium box in the agency guides
None of the agency guides reviewed here, Fannie Mae, VA Pamphlet 26-7 Chapter 12, or the USDA site requirements, define a separate barndominium category. That is good news in one sense: a barndominium is not automatically disqualified. It simply gets evaluated like any other property, which means the outcome depends on the specifics.
What actually decides qualification
Two tests decide the loan. First, standard property eligibility: the structure has to be a conforming residence under the loan program's rules. Second, the appraisal: can the appraiser support the value? Fannie Mae B4-1.3-04 frames it as the property being generally conforming and acceptable in the market area, with the appraisal covering the entire site.
In practice, that means the appraiser needs comparable sales. A barndominium in a market where comparable barndominium and ranch-style homes sell as residences can finance cleanly. A one-of-a-kind build with no comparable sales is where the conversation gets harder, and that is an underwriting question, not a yes-or-no rule.
The typical route to build one: construction-to-permanent
If you are building rather than buying an existing barndominium, construction-to-permanent financing is the typical route, and the verified rules are on the construction-to-permanent loan page: one closing or two, the borrower holds title to the lot, and the lender keeps a Form 1004D or completion alternative plus a certificate of occupancy. The certificate of occupancy is often the pivotal point for a barndominium, because the county's classified use has to support occupancy as a residence.
What to verify with underwriting
- County classification: how the county treats the structure (residential versus agricultural) affects the certificate of occupancy and the appraisal.
- The comparable set: the appraiser needs sales to support value; thin comps are the usual sticking point.
- Agency-specific rules: not verified in this pass, so check with the lender's underwriting for the exact program and property.
Thinking barndominium? Run the property by a lender before you build.
I will take your plans, lot and county classification and tell you honestly whether the financing and the appraisal picture line up, no surprise at the end of the build.
Frequently Asked Questions
Can I get a mortgage for a barndominium in Texas? Tap to expand
Which agencies have barndominium rules? Tap to expand
How do I finance building a barndominium? Tap to expand
What does the appraiser look for on a barndominium? Tap to expand
What should I verify before financing a barndominium? Tap to expand
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Mortgage, LLC (NMLS #1660690). He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country.
Full credentials on the About page · Text or call 210-317-6514
Sincerely,
Patrick Kevin Fagan
Agency guide review and appraisal citation verified September 25, 2026 against Fannie Mae B4-1.3-04. Agency-specific barndominium rules and appraisal comparable standards are unverified in this pass; confirm them with the lender's underwriting.
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
