
Patrick's Quick Answer
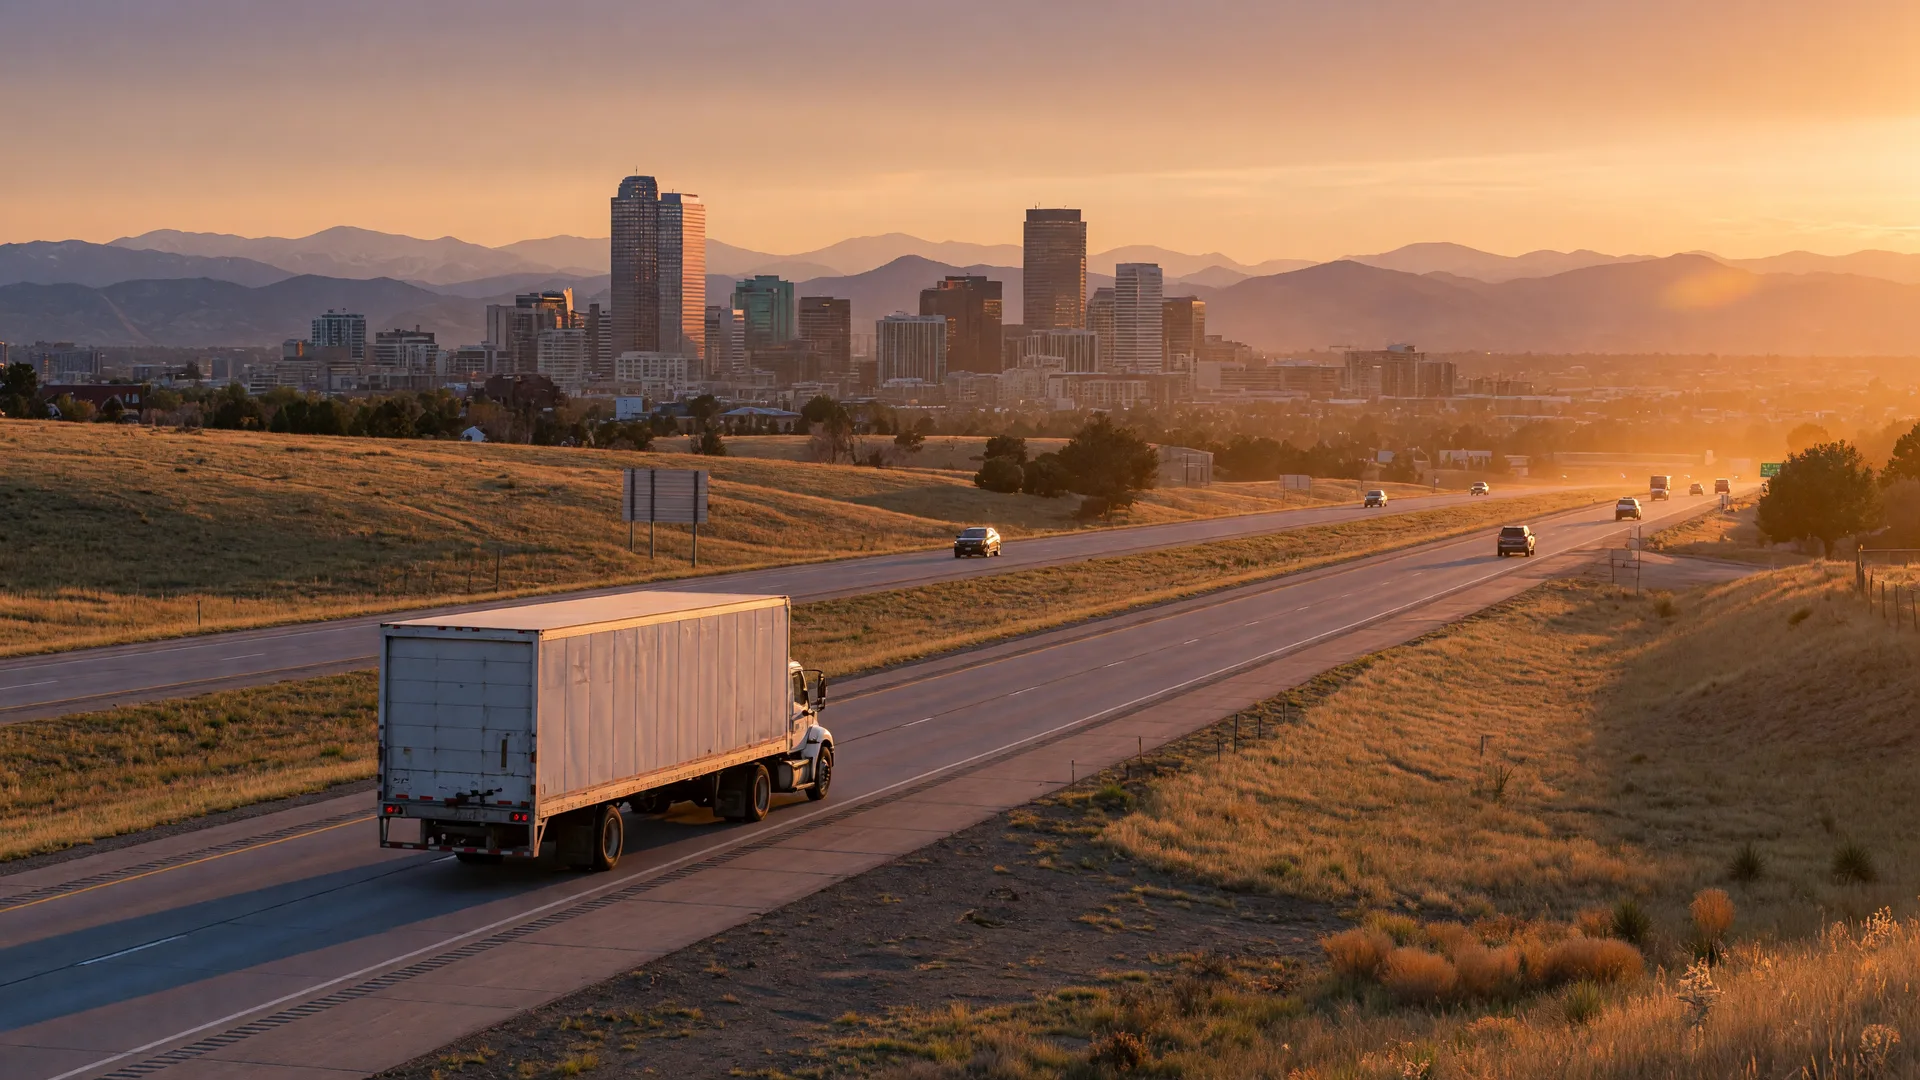
Moving from Denver to San Antonio is the closest price-to-payment pairing in this series so far, and the property tax story runs the opposite direction from most other origins. The Denver median home runs about 2.5 times San Antonio's, about $635,000 (Redfin, three months to June 2026) versus about $257,000 (Redfin, three months to September 2026), yet the complete monthly payment lands only about 2.1 times higher because Colorado's property tax rates sit near a third of Texas's. Colorado's flat 4.4% income tax disappears on arrival, Denver's 9.15% combined sales tax drops to 8.25%, and the hail-heavy Front Range insurance stack gives way to a longer, hotter cooling season. The honest trade is the usual Texas one, higher property tax rates on a far lower price, plus a real summer instead of a mile-high semi-desert climate. As with every post in this series, compare the complete monthly payment, not the price tag.
I work this move from both ends: I originate home loans statewide across Texas, including for Colorado buyers moving here, and I sell real estate around Greater San Antonio, so Denver clients get the financing and the contract side coordinated in one plan. This post is the Denver comparison, with the numbers dated and the sources named. The deeper relocation playbook, with the corridor comparisons and blank payment worksheets, is in the relocation hub.
Why this particular move keeps happening
Colorado to Texas is one of the most consistent interstate corridors in the country, and Texas is the number one destination state for Colorado movers year after year. IRS SOI migration data shows about 13,000 to 13,600 households moving from Colorado to Texas in each of the two most recent analyzed years, roughly 25,000 people a year in each, and the most recent Census Bureau estimates put the 2024 flow near 23,000 Coloradans to Texas, ahead of California and Arizona. The honest caveat before anyone calls it a stampede: Texas sends thousands of households back to Colorado every year too, and Colorado's GDP and job growth have both been strong, so the flow is real but not one-directional (IRS SOI migration data and USAFacts estimates, as compiled by migration trackers).
The families who make this particular move usually name the same three things: a home price that has run well past the national median in the Denver metro, the state income tax line that disappears in Texas, and the size of the house a Texas dollar buys. Denver's median single-family home is more than double San Antonio's, and the gap has widened through the 2020s as the Front Range became one of the pricier mountain-west markets. San Antonio answers with the same tradeoffs the rest of this series documents: a median single-family house at under half the price, zero income tax, a lower combined sales tax, and a milder winter, in exchange for higher property tax rates, hot humid summers, and a flat-land commute that will not remind anyone of the Front Range foothills. Neither city is better; they answer different questions, and because this pairing has the unusual property tax rate flip, this post builds the budget around both, the 2.5-to-one price gap and the annual tax bill that ends up nearly level at the medians.
The two markets, side by side
City-level figures from the same tracker put this pairing in perspective: Denver's median runs about 2.5 times San Antonio's, a narrower gap than the Seattle, Los Angeles, and New York pairings and wider than the Chicago move. One honest caveat before the table: the two tracker snapshots do not cover identical weeks, the Denver figure was captured roughly three months before the San Antonio one, and different trackers define "home" differently. Redfin's Denver median sale price ran about $635,000 in the three months ending June 2026, up about 2.5% year over year, while Zillow's typical-home-value metric for Denver came in lower at about $525,000 because it is a different number, an estimated typical value rather than a median sale price:
| Metric and period | Denver | San Antonio |
|---|---|---|
| City median home sale price (Redfin, three months to June 2026 Denver / Sept 2026 SA) | about $635,000, up about 2.5% year over year | about $257,000, down about 2.9% year over year |
| Ratio of city medians | baseline | about 2.5-to-one cheaper |
| Typical product at the median | single-family house plus a large condo and townhome share, especially inside the urban core | single-family house on its own lot |
| 20% down payment on the city median | about $127,000 | about $51,400 |
| Cost of living, Denver set at 100 (Numbeo, 2026) | 100 (baseline) | about 80, roughly 20% lower including rent, about 16% lower excluding rent |
| State individual income tax | Colorado flat 4.4% with no brackets | none |
Two honest caveats. First, Denver's median hides a real city-versus-suburb spread: inside the urban core and to the west toward the foothills, prices run well past the city number, while east toward Aurora and the airport, the median sits lower, so the corridor matters. Second, the same tracker's historical data shows San Antonio's median drifting down about 2.9% over the last year while Denver's rose, which means a Denver seller who waits tends to see the gap widen, not shrink. The direction of the comparison is clear under every method; the exact size depends on which definition you use.
Cost of living: the mile-high premium versus one of the most affordable metros
Numbeo's comparison, which covers the two cities on the same line items, scores San Antonio about 20% lower including rent and about 16% lower excluding rent, and BestPlaces puts the overall gap near 30% with its own methodology. The rent split is easy to see: a typical one-bedroom in Denver runs about $1,425 to $1,725 a month depending on the tracker (Apartment List, October 2026, and RentCafe, 2026), while a typical one-bedroom in San Antonio runs about $955 to $1,080 (Rent.com and RentCafe, 2026), before you even get to buying:
| Cost of living line (2026 trackers) | Denver | San Antonio |
|---|---|---|
| Overall index, Denver = 100 (Numbeo, 2026) | 100 (baseline) | about 80, roughly 20% lower including rent |
| Typical 1-bedroom rent | about $1,425 to $1,725 a month (Apartment List, RentCafe, 2026) | about $955 to $1,080 a month (Rent.com, RentCafe, 2026) |
| Combined sales tax | 9.15% (Denver city 5.15% plus state, RTD, and SCFD shares) | 8.25% |
| Heating and cooling habit | gas heat and short, dry summers; central air common but not universal on older stock | central air as the practical default, long cooling season |
| Utility pattern | high-altitude dry air, snow-season heat load, occasional summer AC load | long AC season plus irrigation in the warmer months |
Two lines deserve a Denver-specific note. First, the 9.15% combined Denver sales tax is one of the higher city rates in the West, and it applies to the same categories Texas taxes, so the gap on a $50,000 vehicle is about $450 in Denver's favor, San Antonio at 8.25% costs about $4,125 versus about $4,575 in Denver. Second, Denver wages run about 9% to 10% higher than San Antonio's for comparable roles (Salary.com), which partially offsets the cost gap for remote or transferred workers, but that income premium is taxed at Colorado's 4.4% before it ever hits a budget, and the housing line dominates either way. None of these index numbers is a promise for your exact household; they are dated, single-tracker direction on the same line items.
Income tax: Colorado's flat 4.4% versus Texas's zero
Colorado is a flat-tax state, which makes this pairing simpler than the New York or California moves: a single rate of 4.4% applies to all taxable income with no graduated brackets (the rate was 4.55% before a temporary reduction, and Colorado's constitution requires the flat structure). There is no Denver city income tax layered on top. Texas has no individual income tax at all, it is constitutionally prohibited, so the entire line disappears on move.
The cost calculation that matters for a working household, worked with the 4.4% rate and the federal standard deduction: a single filer at about $110,000 gross pays roughly $4,200 a year in Colorado state tax, about $350 a month, and a two-earner household at $220,000 pays roughly double that, before itemized deductions and before Colorado's TABOR refund checks, which have been a real line in most recent years. Move that income to Texas and the line drops to zero. The honest caveats: the year you move is a straddle year, Colorado taxes the portion of the year you were a resident, and Colorado continues to tax some income from Colorado sources for certain situations after you leave, so a qualified tax professional should confirm your personal picture. Nothing here is tax advice.
Property taxes: the rate flip that surprises Denver sellers
This is the section that sets this pairing apart from every other origin in the series. Denver's residential property tax rate is roughly a third of San Antonio's, so the usual "the rate is higher and the bill is higher" Texas story does not hold at the median. Denver County's median effective residential rate runs about 0.48% to 0.55% of market value, calculated through Colorado's split assessment system, while San Antonio's median effective rate runs about 1.55% with a typical combined in-city rate near 2.27% of taxable value. The rates land where they do because Texas funds much more local government and schools through property tax, while Colorado sets residential assessments low by constitutional formula:
| Property tax line (2026 sources) | Denver | San Antonio / Bexar County |
|---|---|---|
| Effective tax rate on market value | about 0.48% to 0.55% median effective, via split residential assessment and mill levies | about 1.55% median effective; about 2.27% combined in-city rate on taxable value |
| Estimated annual bill on a median-priced home | about $3,200 on $635,000 | about $4,000 on $257,000 |
| Estimated annual bill on a $500,000 home | about $2,500 | about $7,750 at the median effective rate |
| How value is set | Colorado split assessment: residential local value at 6.25% times local mills plus school value at 7.05% times school mills | appraisal district sets value each January, with district rates applied on top |
| Owner protections | TABOR caps on revenue growth and assessment-rate limits set by law | 10% annual homestead appraisal cap, homestead exemption filed after closing, annual protest window |
The dollar read is the headline, and it is the opposite of the California and New York posts: median to median, the annual property tax bill barely moves, about $3,200 in Denver versus about $4,000 in San Antonio, even though the Denver home costs two and a half times as much. What does change is the fixed-price read, a $500,000 home carries about $2,500 a year in Denver and roughly $7,750 in San Antonio, before the Texas homestead exemption and the 10% appraisal cap are filed, and those filings matter for your first year. The property taxes in San Antonio explainer and the homestead exemption guide cover the filing steps, and the exact address, district, and exemptions decide the real number in either county.
The monthly payment: same budget, both cities
Price is not payment, and this pairing shows why better than most. These are illustrative numbers, dated October 2026, run on the series' standard assumption set: a 30-year fixed mortgage at 6.5%, 20% down, principal and interest plus an annual property tax estimate at each area's effective rate, with no insurance, HOA, or mortgage insurance included. They exist to compare the two cities on the same math, not to quote a rate or approve a loan:
| Illustrative line, dated Oct 2026 | Denver median | San Antonio median |
|---|---|---|
| Home price | $635,000 | $257,000 |
| 20% down payment | $127,000 | $51,400 |
| Loan amount | $508,000 | $205,600 |
| Principal and interest at 6.5%, 30-year fixed | about $3,210 a month | about $1,300 a month |
| Property tax at each area's effective rate | about $265 a month | about $330 a month |
| Estimated complete P&I + tax payment | about $3,480 a month | about $1,630 a month |
That is about a 2.1-to-one payment gap, noticeably narrower than the 2.5-to-one price gap, because Denver's low property tax rate softens the payment difference. The flip side is where this move usually wins: a household carrying the Denver median payment of about $3,480 a month, run through the same assumptions in San Antonio's tax environment, can support about a $620,000 home, roughly 2.4 times the San Antonio median, which buys a large single-family house on a real lot in most of the market. Sell in Denver, buy in San Antonio, keep the payment roughly the same and take the bigger house, the zero income tax, and the milder winter. Add the Colorado income tax line that disappears, about $350 a month at the example above, and the cash-flow story reads even better.
Cash to close: what actually changes hands
The down payment is not the whole cash number, and the Texas side has a few lines that settle differently than Colorado. On a Texas purchase, cash to close includes the down payment plus an owner's title policy, which is a real and expected line here, lender origination and third-party fees, and prepaids for property taxes and homeowners insurance at closing. Texas adds no mortgage recording tax and no transfer tax on the purchase side, and many buyers negotiate a seller credit toward these costs inside the TREC contract. The option period is the Texas feature Denver buyers notice first: a defined window, typically 7 to 10 days, to run inspections and negotiate repairs before you are locked in, which is very different from a no-contingency Colorado offer in a hot market.
The timing works in your favor if you plan it: a Denver sale and a San Antonio purchase can run on overlapping calendars, the Texas option period gives an out-of-town buyer a real verifying window that video tours cannot, and Texas down payment assistance programs (TSAHC and My First Texas Home among them) are available to many first-time buyers, which matters if the Denver equity is not coming with you. The closing costs in Texas guide and the cash to close explainer show exactly where the money lands on the Texas side, and getting pre-approved before you book the flight is the step that keeps the relocation deadline from becoming a fire drill.
Climate: snowfall gives way to heat, but the sun follows you
This pairing swaps Colorado's high-plains chill for the longest cooling season in Texas, and the numbers are among the cleanest in the series. Denver gets about 14.3 inches of precipitation a year with about 47 inches of snow, a July high near 90, and a January low near 19 (NOAA 1991-2020 normals at Denver International). San Antonio gets about 32.4 inches of precipitation across roughly 81 wet days, about 0.2 inches of snow a year, a July high near 95, and a January low near 39 (NOAA 1991-2020 normals). In other words, the snowfall almost completely disappears while the summer heat rises about five degrees, and both cities clear out on the sunshine side of the ledger.
The sunshine claim deserves an honest footnote, because Denver's marketing exceeds its data: Denver actually gets about 69% of possible sunshine, roughly 252 equivalent full-sunny days a year, which is still genuinely sunny but not the "300 days" figure the city's slogan suggests (Colorado Sun, 2024). The practical reset for a Denver transplant is the reverse of the California move: instead of giving up a temperate coast, you trade the snow shovel and the winter tire rotation for a real cooling season, longer pool time, and an AC system that runs a big share of the year. The summer utility bill takes over the budget line the January heating bill used to occupy, and the rain timing changes too, Denver's precipitation is light and spread out, while San Antonio's arrives in bursts, so the flood zone check at the exact address belongs in every diligence list, same as it does in Denver.
Denver house habits that reset on arrival
A few Denver assumptions need adjusting on arrival, and they show up more than you might think:
- The mile-high reality ends. Denver sits at 5,280 feet, water boils around 202 degrees there, recipes and bake times carry altitude notes, and the first few days of exertion feel different. San Antonio sits near 650 feet. The altitude is a lifestyle line, not a housing line, but it is the first thing every Denver transplant notices.
- The snow stack retires. Denver averages about 47 inches of snow a year, so shovels, scrapers, winter tires, and cold-start routines are part of the house rhythm. San Antonio averages about 0.2 inches a year, and winter weather is a rare week at most, so the garage space frees up immediately.
- The AC question flips. Denver's short, dry summers historically left a share of older homes without central air, with evaporative coolers and window units still present in the older stock. In San Antonio the question is never "does it have AC?" but "how old is the system and does it cover the whole house?" Check the system age at inspection and budget for the cooling season.
- Water thinking changes. Colorado runs a prior-appropriation water system where water rights are legally separate from the land, and while most Denver metro homes sit on municipal water through Denver Water, the water-rights question follows any well or irrigated acreage purchase. San Antonio homes tie into the water system, and in the Hill Country corridors, wells and septic on unincorporated land are part of the deal instead, a different checklist entirely.
- The mountains turn into hills. The Front Range's 80-mile daily backdrop becomes the Hill Country's limestone and live-oak terrain. The honest neighborhood comparison is never terrain nostalgia; it is commute, lot size, schools, utilities, and tax district, exactly what the corridor guides below cover.
- The commute model differs. Denver's rush hour is an I-25 and I-70 story, with a light rail system that sets a car-light option for some corridors. San Antonio is a loop-city commute, 1604, I-10, and I-35, almost entirely by car, so the honest planning step is to test the route at the time of day you would actually drive it before you commit to a corridor.
Hail, insurance, and the Front Range maintenance stack
No Denver-to-San Antonio comparison is complete without the hail line, because it drives the single biggest housing-cost variable that is not a mortgage. The Front Range sits in the heart of "Hail Alley," the highest-frequency large-hail zone in North America, and Denver averages 7 to 9 significant hail days a year, with seven of Colorado's ten costliest hailstorms hitting the Denver metro. Bexar County by comparison averages about 3.1 days a year with hail of at least one inch (NOAA Storm Events Database, 1970-2024). Colorado is a top-two state for hail damage claims, wind and hail is the biggest driver of homeowners insurance cost there, and catastrophic-hail deductibles are commonly quoted separately at $2,500 to $10,000 or 1% to 5% of dwelling coverage:
| Home and weather reality | Denver | San Antonio |
|---|---|---|
| Significant hail days per year | about 7 to 9 (Hail Alley, top in North America) | about 3.1 days a year with 1-inch hail or larger |
| Main severe-weather cost driver | wind and hail, with separate catastrophic-hail deductibles common | hail on the I-35 corridor plus heat, with statewide premium pressure |
| Typical hail deductible structure | $2,500 to $10,000 flat, or 1% to 5% of dwelling coverage | standard deductible structure, though carriers vary by address |
| Wildfire smoke and air quality | summer smoke events from Western fires trigger periodic alerts | occasional smoke drift from far fires, not a routine summer line |
| Radon potential | EPA highest-potential zone, testing widely recommended | testing is cheap either way and part of good diligence |
The honest read is not that San Antonio insurance is cheap, Texas premiums have been rising statewide, but that the per-event hail exposure and the separate catastrophic-hail deductible structure that Colorado homeowners carry are not the default setup here. The practical advice is identical in both states: get an insurance quote for the exact address before you commit, ask for the hail and wind deductible in writing, check the roof age and condition at inspection, and know what a claim would cost you out of pocket. The San Antonio home insurance rates explainer covers the local side of that question.
The trip: two hours by air, a day and a half by truck
Denver to San Antonio is about 933 miles by road, and the I-25 to I-40 to I-35 routing drives in roughly 14 hours straight through, with stops and a hotel night meaning most families plan it as a day and a half or two days (Travelmath; Rome2rio). By air the trip is about 800 miles along the great circle, and nonstop flights between Denver International and San Antonio International run about 2 hours 5 minutes to 2 hours 25 minutes (United, Southwest, and Frontier fly the route nonstop; verify current schedules before booking).
This is a genuinely convenient distance: both cities are hub-and-spoke friendly, the flight is shorter than the New York and Seattle legs in this series, and a long-weekend house-hunting trip is practical. The pattern that works most often: verify financing first, shortlist on video, fly down for the option period and inspection, close, and let the household goods arrive on their own schedule. For remote and hybrid workers the move is even simpler, and Denver's share of remote-capable jobs is high, but the honest planning step is the same for any distance move, pre-approval before the trip, not after.
The military move: from Buckley SFB to JBSA
The Denver metro's military anchor is Buckley Space Force Base in Aurora, on the east side of the city, and orders from Buckley and other Front Range stations flow regularly to Joint Base San Antonio, which combines Lackland, Randolph, and Fort Sam Houston, home of the military's Medical Education and Training Campus. For a service member or family on those orders, the housing question is always the same: what does the housing allowance buy at each station? The 2026 rates tell the story, and it runs the opposite direction from most PCS moves in this series:
| 2026 BAH, E-5 with dependents | Rate | Share of the local median payment |
|---|---|---|
| Denver metro military housing area (MHA CO045, covers Buckley SFB) | about $2,841 a month | about 82% of the Denver median payment on the series' standard assumptions |
| San Antonio (MHA TX285, JBSA) | about $1,869 a month | about 115% of the San Antonio median payment on the same assumptions |
That table is illustrative arithmetic with a stated assumption set, not a promise, and every service member's file differs by rank, dependency status, and the specific home. The honest read: the BAH number drops by about a third between the two areas, but the median home payment drops by more than half, so the allowance covers a larger share of a median-priced home in San Antonio, and on the series math it covers the whole median payment and a little more. The VA loan itself works the same in both states: 0% down, no monthly mortgage insurance, and a one-time funding fee that runs about 2.15% of the loan for first-time use with less than 5% down (about 3.30% for subsequent use), with the fee waived for veterans receiving VA disability compensation. VA financing is a specialty of mine, and the VA loans for JBSA buyers guide, the best towns per base guide, and the orders-to-keys PCS guide cover the timing, the paperwork, and the corridor comparisons.
Where you land in San Antonio
Denver transplants land all over the San Antonio area, and the honest answer is that the right corridor depends on your commute, your budget, and the property type you want. This market splits into a few corridors, each with a full guide in our community library:
- I-35 northeast, Schertz, Cibolo, and New Braunfels: town and suburban homes with city services, the fastest-growing family corridor in the area and a short highway hop to downtown and Randolph, which makes it the default for military families. New Braunfels guide.
- US-281 north, Bulverde and Spring Branch: larger lots and Hill Country terrain, with much of the corridor unincorporated, so wells, septic, and utility districts are common. Bulverde guide.
- I-10 west, Boerne and Fair Oaks Ranch: a town with its own services plus master-planned communities that cross Kendall, Bexar, and Comal County lines. Boerne guide.
- Canyon Lake: lake-country acreage and resort-style communities in unincorporated Comal County, quiet and spread out rather than walkable. Canyon Lake guide.
Denver buyers also notice one thing the Front Range does differently: Texas property is overwhelmingly fee-simple with a garage, a yard, and a defined lot, and the price per square foot runs well below the Denver median even after the buyer's-market discount east of I-25. Each corridor carries its own county, school district, appraisal district, utility mix, and tax jurisdictions, so the comparison is never "metro versus metro" but "exact address versus exact address." The relocation hub compares all the corridors on the complete monthly payment without declaring a universal winner, because there is not one.
Questions buyers ask before this move
Does Colorado's 4.4% flat income tax really disappear when I move to Texas? Tap to expand
San Antonio's property tax rate is higher, so why do the median bills land so close? Tap to expand
How real is the hail and home insurance difference between Denver and San Antonio? Tap to expand
I'm PCSing from Buckley Space Force Base to Joint Base San Antonio. Can I use a VA loan? Tap to expand
Making the move? Let's put the numbers on paper.
I work the financing and the real estate side of the same move, so the price, the Texas tax load, the Colorado income tax math you leave behind, the cash to close, and the offer strategy get coordinated in one plan. Bring your Denver numbers, sale proceeds or not, and I will show you what they do in San Antonio.
A buyer who went through the process put it this way: "He's very responsive, professional, and will clearly explain every step of your buying process, and best of all he was able to keep some money in my pocket." More client words are on the reviews page.
About Patrick Kevin Fagan, REALTOR®
Patrick Kevin Fagan is a Texas Real Estate Sales Agent (#454749) with AXEN Realty LLC and a Senior Loan Officer (NMLS ID #877741) with NEXA Lending. He brings 23+ years in mortgage lending and 19 years in real estate, serving homebuyers, homeowners, and sellers across Greater San Antonio and the Texas Hill Country, and originates home loans statewide across Texas, including for Colorado buyers moving in. VA financing is a specialty, and the deeper relocation playbook, with the migration data and blank payment worksheets, is in the relocation hub.
Sincerely, Patrick Kevin Fagan
Answered by Patrick Kevin Fagan
Texas Real Estate Sales Agent #454749, AXEN Realty LLC · Senior Loan Officer, NMLS ID #877741, NEXA Mortgage, LLC
Call or text: 210-317-6514
Updated October 23, 2026. Median price, cost of living, income tax, sales tax, property tax, BAH, and climate figures are dated, single-tracker snapshots (sources named in the post) and are directional, not forecasts or quotes. The income tax figure is a worked estimate using Colorado's 4.4% flat rate and the federal standard deduction for a single filer, and it is not tax advice. Payment math is illustrative arithmetic for comparison using a stated assumption set, never a rate quote or an approval. BAH figures are official 2026 rates; what they cover depends on the specific home and the complete payment. Colorado and Texas tax treatment of a home sale and of residency is a qualified tax professional's question. Verify the appraisal district record, tax rates, insurance quotes including hail and wind deductibles, utility types, HOA documents, AC age, roof condition, radon results, and school district for the exact address before you commit. Nothing here is neighborhood steering or a claim that any area is better for any person or group; area fit is personal, and fair housing law applies to every inquiry.
