
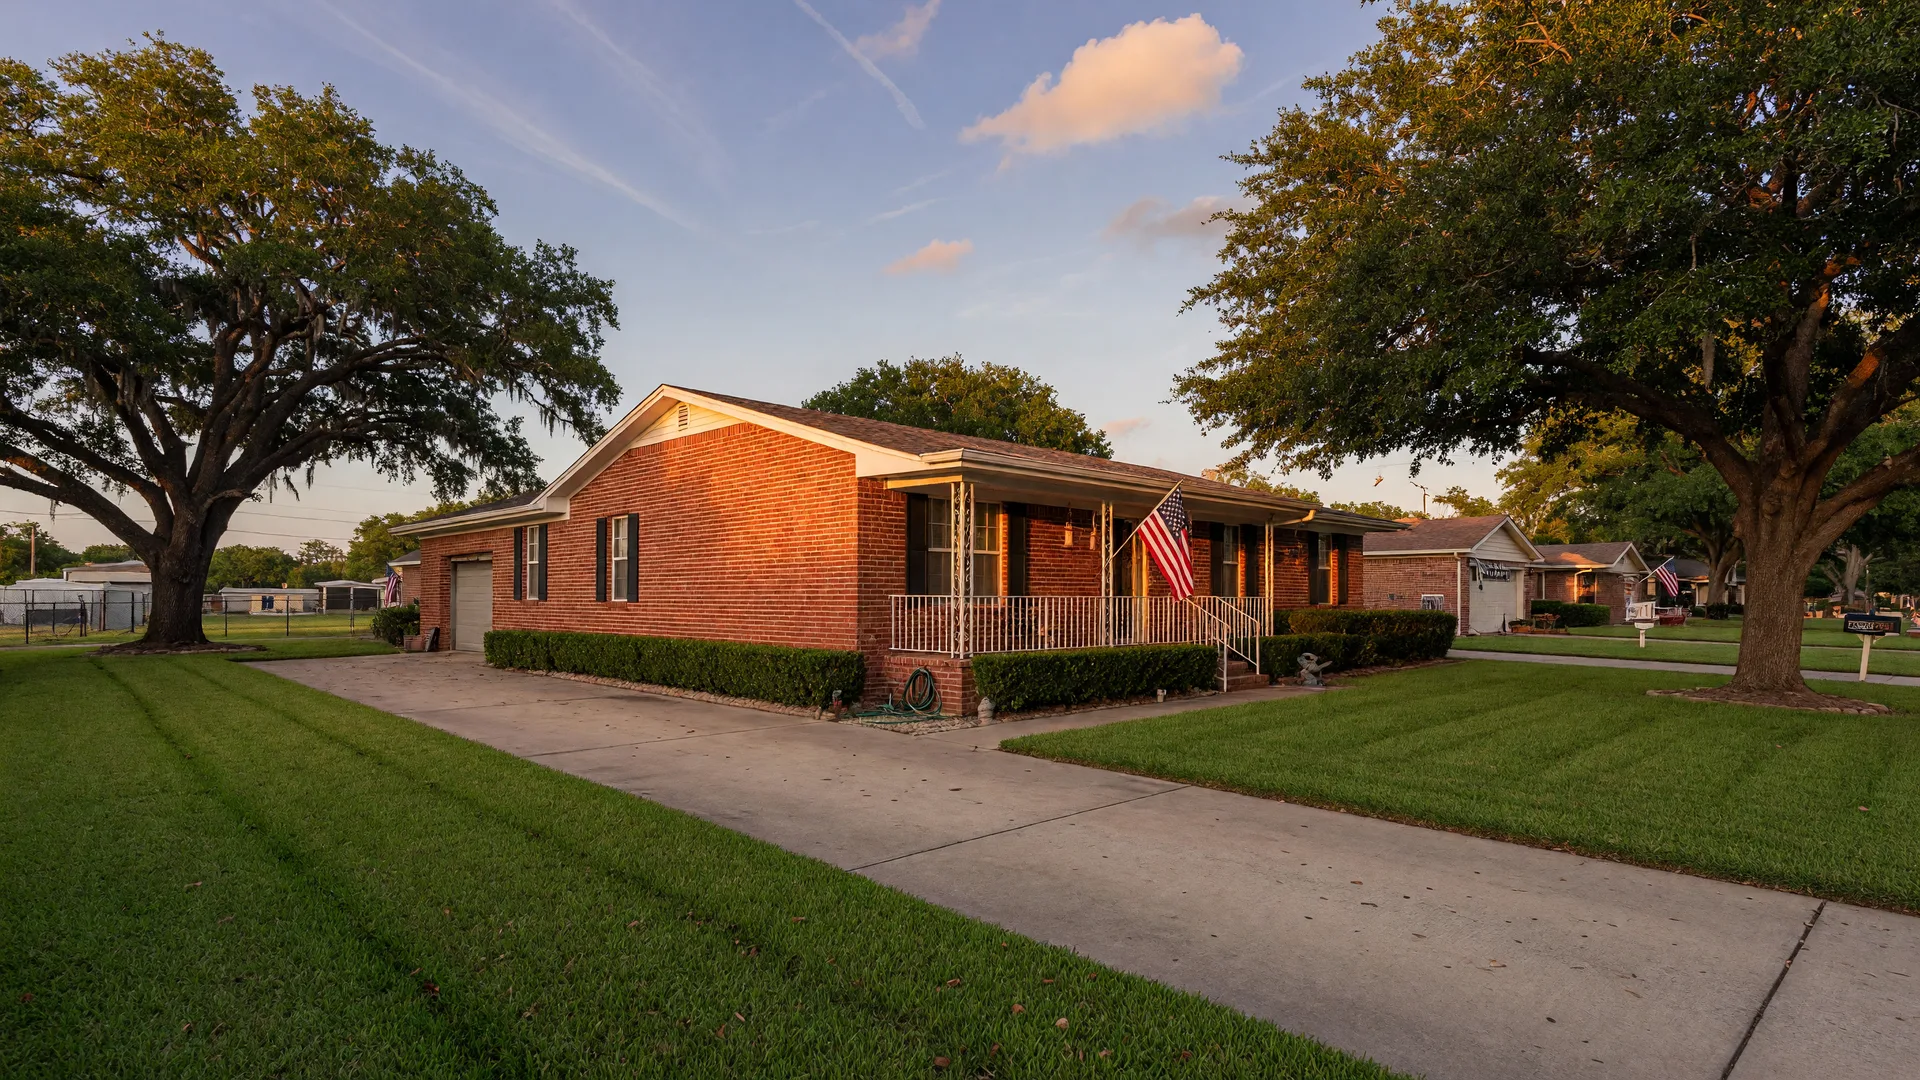
Patrick's Quick Answer
If you are eligible for the VA loan benefit, in most cases you can buy in the San Antonio metro with $0 down, no monthly mortgage insurance, and access to some of the most competitive financing in the country, and the San Antonio area is one of the best military real estate markets in the US because of Joint Base San Antonio. For families PCSing in 2026, the edge comes from using the benefit properly: getting your COE early, working with a lender who closes VA loans often, and negotiating like a normal buyer in a market that currently favors them.
Here is the practical walk-through, from someone who has originated VA loans for buyers in and around JBSA.
Why San Antonio is a military homebuying market
Joint Base San Antonio anchors the metro: Fort Sam Houston, Lackland, and Randolph, with thousands of families PCSing in and out of the area every year. That steady flow of service families is part of the reason this market stays liquid in every rate environment. You are not buying into a niche; you are buying into steady demand that holds up across rate cycles, which makes the area a sound place to own through multi-year tours.
The practical consequence is that VA loans are not exotic here. Appraisers, title companies, and agents around the base all work VA deals routinely, which removes most of the "nobody does VA" friction you can run into elsewhere in the state.
The VA advantage
Here is what the benefit actually buys you in 2026:
- Zero down payment in most cases. No 20% requirement, and no "small down payment" story the way conventional loans have.
- No monthly mortgage insurance. The program does not carry PMI, which is a real monthly difference compared to a 3.5% down conventional loan.
- Competitive interest rates. VA loans typically sit in a healthy spot in the rate stack, and the funding fee can be waived or reduced for disability-rated veterans and some other cases.
- The benefit is reusable. Once a previous loan is paid in full or sold, the entitlement can be restored and used again.
I am not printing funding fee percentages or rate numbers because they change and because your file matters. The features above are the fixed, general structure of the program.
PCSing to JBSA with a tight window?
The right sequence is short: COE, pre-approval, tour, offer. I have done this timing enough times to know exactly where the bottlenecks live. A 15-minute call saves the guesswork.
What trips up first-time VA buyers
The VA benefit is strong, but four things stall otherwise smooth files:
- Not having your Certificate of Eligibility ready. The COE is the document that proves you have a benefit, and waiting until week four to request it is the classic avoidable delay.
- Working with a lender who rarely does VA. VA underwriting has its own protocol; an experienced VA lender knows what stops a file before it starts.
- Underestimating the VA appraisal. The VA's appraisal considers both value and property condition, and its requirements are not the same as an FHA or conventional inspector's list. It protects you, and it takes time.
- The county loan limits question. In some cases county limits apply; in others they do not, depending on whether you still have entitlement tied to a previous loan. Check your specific situation rather than assuming.
Three 2026 tips for PCS families
- Get your COE early, even before you pick a lender. It is free through the VA and it takes days, not hours, so do it the week you get orders.
- Get pre-approved before house hunting. Military moves run on a timeline that does not respect a 40 day escrow, and a pre-approval lets you compress your to weekends you actually have.
- Negotiate like a normal buyer. A VA loan is not a disadvantage in 2026. With more inventory and longer listing times, sellers are often open to financing terms, including VA, and your offer strength comes from your pre-approval and your terms, not from a down payment size.
Who can use the benefit
Eligible homebuyers include veterans, active duty service members, reservists, and National Guard members, and in some cases surviving spouses. Eligibility is a checkable fact, not a vibe: confirm your status at va.gov before you build a plan around it.
If you have served, the benefit is part of your paycheck of service. Use it, and use it with people who close it often.
Frequently Asked Questions
Can I use my VA loan in San Antonio, Helotes, and the Hill Country suburbs? Tap to expand
Can I use my benefit again after my previous loan is paid off? Tap to expand
Is a VA loan weaker in a multiple offer situation? Tap to expand
Before you make the move, take 15 minutes.
We will run your benefit eligibility, the timelines for your PCS, and how the VA numbers land on the properties around JBSA. If your COE is missing, we will start it the same day.
Patrick Kevin Fagan
Loan Officer and Realtor | AXEN Realty LLC | San Antonio and Texas Hill Country
Licensed Sales Agent | 454749 | TX
Sincerely, Patrick Kevin Fagan
This article describes general features of the VA home loan benefit. Exact eligibility, funding fee status, loan limits, and rates vary by borrower and over time; confirm yours through the VA at va.gov and with your lender.

