
Patrick's Quick Answer
Yes, the VA loan can finance a home with acreage near San Antonio, and it brings the same package you know: zero down, no monthly mortgage insurance, and a reusable benefit. The one thing to plan for is how VA treats land. The home and the land have to be reasonable together, meaning the appraiser verifies the value supports the price, including how much of it is dirt. With JBSA nearby, this is a popular route for military families who want the Hill Country without giving up the VA benefit, and it works on wells and septic too.
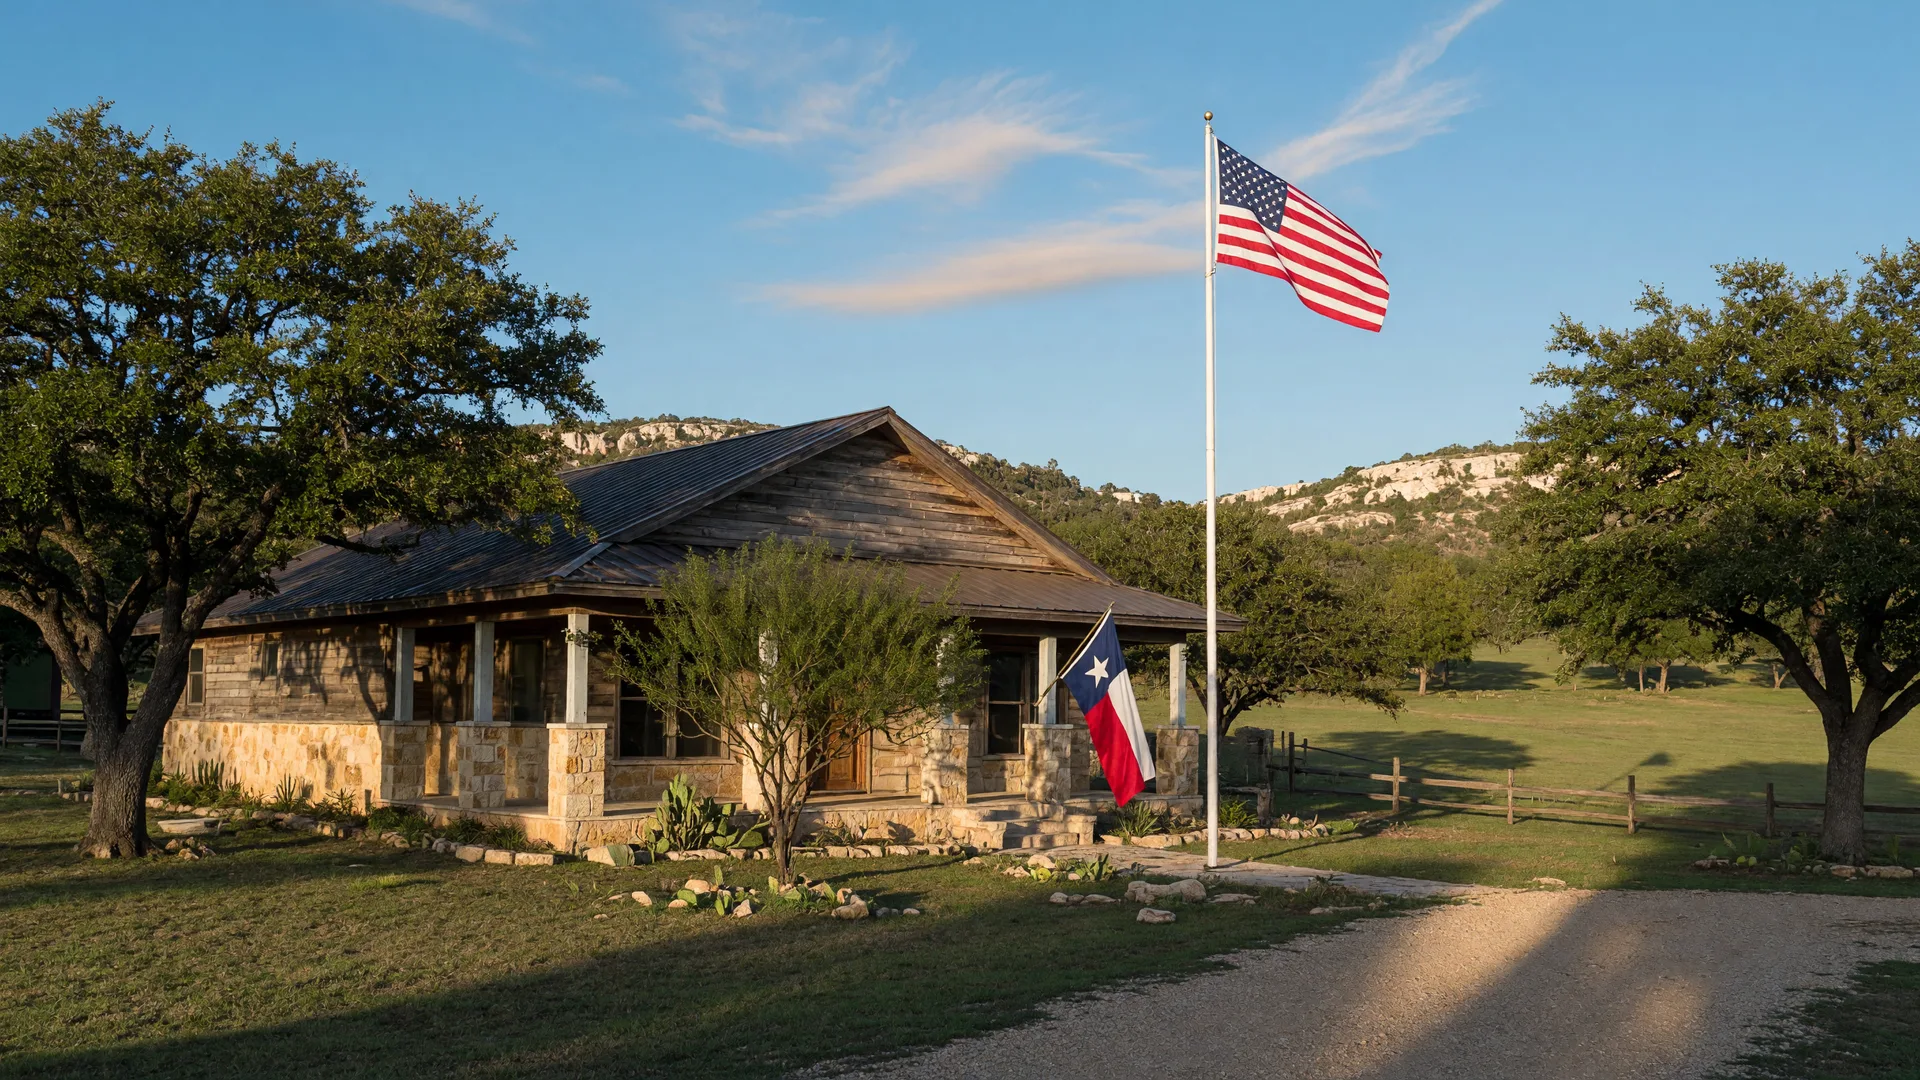
A lot of military families stationed at JBSA Fort Sam Houston, Randolph, or Lackland ask me whether they can use their VA loan to escape city life and buy a few acres in the Hill Country. Good news: that's exactly what the program is for, as long as you follow its rules.
What the VA loan offers
Quick refresher on why the VA loan is worth protecting: zero down payment for qualified veterans and service members, a competitive rate, no monthly private mortgage insurance, and a benefit you can reuse after you sell or refinance. There are closing costs and a funding fee (with exemptions for disability-rated veterans) but no PMI, and that keeps monthly payments lower than a comparable FHA or conventional deal.
Every one of those features applies whether the home sits on a quarter-acre in Schertz or ten acres near Spring Branch. The program doesn't start making exceptions because there's grass. My VA home buying guide covers the base package in full.
How VA handles acreage
The area where acreage changes the deal is the appraisal. VA's appraiser looks at the property and answers one core question: does the value support the price? On acreage, that means the appraiser considers the land's contribution, the location, and the improvements, and makes sure you're not paying a premium that the market won't support.
VA also applies what's called the reasonable value requirement: the loan amount can't exceed the appraised value, and if the appraisal comes in low, you and the seller renegotiate or you make up the difference. I won't quote you fake thresholds, because the exact math depends on the property, but I will tell you the practical rule: the home needs to be a real, liveable residence with the land as a reasonable bonus, not a hunting camp with a cabin and 90% of the value in acres.
That is precisely why comps matter. VA compares your property to similar homes with similar land. If your ranch-style home on three acres is being compared to tract homes on lots, the appraiser adjusts for the land, and buyers who understand that adjustment aren't surprised on appraisal day.
Here's the key: on a VA acreage purchase, the appraisal is the deal. Order comps in the right land class, confirm the improvements are solid and current, and don't let the ranch romance outrun the value data.
JBSA ties and the local market
San Antonio is one of the largest military markets in the country, with JBSA installations spread across the metro, and the Hill Country north of town is a favorite for PCS families who want space after base housing. The 281 corridor toward Bulverde, Spring Branch, and beyond stays popular because it offers acreage without leaving the metro's job and hospital network.
The practical consequence: well-priced acreage homes near the corridor move, and sellers know VA buyers come pre-screened by a lender. The advantage of using your VA entitlement here is that your benefit is exactly as strong on a ranchette as it is on a townhouse, and local sellers have seen VA deals close clean.
VA plus well and septic properties
A VA loan works fine on well and septic, with conditions. VA requires the well to have adequate flow and a clean water quality test, and the septic to be inspected and functioning. If the well is shared or the septic is undersized, that's a fix-before-close conversation. The VA appraiser will note anything that looks like a safety or health issue, similar to what a buyer's inspection would catch.
My advice stays the same as any well and septic property: run the tests during the option period and give yourself room to negotiate. I walk through the whole routine in my wells and septic guide.
The steps to use it
- Get your Certificate of Eligibility. COEs are quick to pull online and tell your lender how much entitlement you have available.
- Work with a lender who does VA acreage. The niche details, Texas-specific rules included, matter, and not every shop has done land deals.
- Get pre-approved for the acreage target price. Knowing your ceiling including land keeps you honest when the pretty property shows up.
- Order the well and septic work in the option period so the appraisal and the loan conditions align.
- Close. Same as any VA purchase, with a funding fee or exemption based on your status.
Used your VA entitlement on a home before? Let's check what's left.
Your benefit may be reusable, and the rules on entitlement restoration changed over time. I'll run your COE picture and show you exactly how the acreage purchase would be structured.
Frequently Asked Questions
Can I use my VA loan to buy land with a house anywhere in the Hill Country? Tap to expand
Does VA have a maximum acreage? Tap to expand
What if the VA appraisal comes in low on an acreage property? Tap to expand
Let's structure your VA acreage purchase
From the COE to the appraisal to the well test, I can run the entire VA country-home playbook with you, whether you're PCS-ing to JBSA or already here.
Patrick Kevin Fagan
Loan Officer and Realtor | AXEN Realty LLC | San Antonio and Texas Hill Country
Licensed Sales Agent | 454749 | TX
Sincerely, Patrick Kevin Fagan
VA program details in this post are directional and change with VA policy. Confirm the current requirements with your lender and the official VA resources before relying on any detail.

